Fund of the Week: 3i, LP

3i, LP is a Delaware limited partnership that lends into distressed and cash-constrained microcap issuers through senior secured convertible notes and non-voting convertible preferred stock, and takes collateral over the borrower's assets. Twice in the past six weeks it has also attached a percentage-of-revenue royalty to that lending. It is managed by 3i Management LLC, a New York firm that states on its own site it is not associated with 3i Group plc or any of its affiliates.
The manager's public presence stops there. There is no disclosed fund size and no LP roster, and no Form D has been filed under 3i, LP's own SEC identifier (CIK 0001841619) to indicate it has itself raised capital from outside investors. What exists instead is a filing history of more than eighty Schedule 13D and 13G statements since January 2021, a UCC Article 9 foreclosure sale it conducted as collateral agent in December 2025, three pieces of litigation against a single borrower, and, as of 10 September 2026, a royalty-repayment facility in a Nasdaq-listed CNS oncology company.
At a Glance
- What it is: a Delaware limited partnership providing senior secured convertible debt and non-voting convertible preferred stock to microcap and small-cap issuers, typically alongside warrants
- Manager and general partner: 3i Management LLC, a Delaware limited liability company, also general partner of Tumim Stone Capital
- Named principal: Maier Joshua Tarlow, who signs as Manager of 3i Management LLC on every reviewed filing, from the 2023 CNBX Schedule 13G to the 2026 Netcapital amendment
- Addresses of record: a mailing address at 140 Broadway, 38th Floor, New York, and a Delaware registered-agent address at 874 Walker Road, Suite C, Dover, per its SEC filer record; recent letter agreements give 2 Wooster Street, 2nd Floor, New York, as the operating address, attention Maier J. Tarlow, as in the Valion Bio side letters
- SEC filer history: Schedule 13D and 13G filings under CIK 0001841619 run from 25 January 2021 to 4 September 2026, with no Form D on the same CIK
- Fund size, LP base, founding date, track record: not published anywhere found
- Current positions: Fintel's tracker lists 16 current 13D/13G positions with a combined reported value of $17.8M
- Royalty interests held: two, both written into 3i's own 2026 lending rather than acquired from a third party
A Note on Scope
3i, LP is not 3i Group plc, the London-listed private equity and infrastructure manager, nor 3i Infrastructure plc, its listed investment trust. The manager's own site carries the disclaimer because the name collision is real: EDGAR carries a separate and older family of "3i" filers, including 3i Growth Capital funds and 3i North American Infrastructure vehicles tied to the UK firm, with their own CIKs and their own London or 3i Group addresses.
None of those entities appear in this profile. Every filing and contract cited here runs through CIK 0001841619, and its business is exclusively microcap structured finance in the United States.
3i publishes no fund list, no LP roster, no performance figures and no terms. Everything quantitative below is drawn from SEC filings under 3i's own CIK, borrower 8-Ks, S-1s and proxy statements, court dockets, and financial-news reporting on those same filings, since those are the only channels that disclose 3i's deal terms at all.
Investment Thesis and Mandate
No strategy document, pitch deck or fund prospectus for 3i, LP has surfaced in this research. The mandate has to be read from the transactions themselves, and they describe a consistent counterparty profile: small-cap and micro-cap issuers, frequently biotech or diagnostics names, in financial distress or with limited access to conventional capital markets, raising money through privately placed convertible debt or convertible preferred stock under Section 4(a)(2) or Rule 506(b) exemptions.
The earliest documented transaction is a $2.5M private placement of senior secured convertible notes into Cannabics Pharmaceuticals Inc., the company now trading as CNBX Pharmaceuticals Inc., closed 16 December 2020. 3i's earliest SEC beneficial-ownership filing under its own CIK, a Schedule 13G, is dated 25 January 2021.
Every deal reviewed since has followed one of two structures: a convertible note secured against the borrower's assets, or convertible preferred stock. Nearly every equity-linked case adds a contractual blocker limiting 3i's beneficial ownership of the issuer's common stock to 9.9 or 9.99 percent, regardless of how much stock the underlying instruments could otherwise convert into.
How Capital Enters and Returns
Capital in. 3i does not appear to hold a fund with third-party limited partners in any form visible on EDGAR. It reports only as a Schedule 13D or 13G filer, never as a Form D issuer, which would be the marker of 3i itself selling limited partnership interests to outside capital. Every dollar deployed in the deals reviewed is described as 3i's own capital, with Valion Bio's Schedule 13D naming "working capital (WC)" as the source of funds.
Conversion, warrants and blockers. The note structure typically carries a fixed conversion price set at closing and a floor price below which the borrower cannot be forced to convert, and that floor is frequently renegotiated downward as the borrower's stock falls. In Valion Bio, the Series B floor price was cut from $1.294 to $0.39 per share as part of the December 2025 restructuring.
In Banzai International, four successive note closings between June 2025 and February 2026 carried conversion prices of $1.11 to $22.20 depending on the tranche. Warrants accompany nearly every note or preferred tranche, priced separately from the note's own conversion terms.
Collateral, foreclosure and royalty repayment. Several deals give 3i a security interest in the borrower's assets rather than only a conversion right, and one, Scorpius Holdings, ran all the way to a UCC Article 9 foreclosure sale with 3i as collateral agent. Since August 2026, two deals also return capital through a gross-revenue royalty rather than through conversion or interest alone. The mechanical skeleton recurs across borrowers with no obvious sector pattern: cannabinoid therapeutics, marine vehicles, education services, energy exploration and CNS oncology diagnostics all carry variants of the same instrument set.
Financial Profile and Assets
| Item | Amount | Source and Date |
|---|---|---|
| Reported current portfolio value | $17.8M across 16 positions | Fintel, 2026 |
| Earliest documented 3i deal (Cannabics/CNBX note) | $2.5M | MarketScreener, 16 Dec 2020 |
| Scorpius Holdings original secured notes (3i + Sabby) | $12,416,667 + $972,222 | SEC 8-K, 6 Dec 2024 |
| Scorpius foreclosure sale, net proceeds | $15,219,552 | SEC 8-K/A, Mar 2026 |
| Valion Bio Note Purchase Agreement (funding the Scorpius asset buy) | $16,253,147.10 plus a warrant over 4,553,213 shares | SEC 8-K, 9 Dec 2025 |
| Valion Bio Series C Preferred facility, aggregate | up to $75,000,000 | S-1, 2026 |
| Valion Bio / Velocity Bioworks royalty | 5% of gross revenue for 10 years | 8-K, Ex. 10.2, 17 Aug 2026 |
| Banzai International notes, aggregate original principal | $11.0M | 424B3, Jun 2025 to Feb 2026 |
| CNBX Pharmaceuticals shares issued to 3i on conversion | 100,000,000 shares, against a further 24,946,375 issuable | Schedule 13G/A, Amdt. 8, 17 Mar 2026 |
| CNBX Pharmaceuticals shares outstanding | 1,225,768,095 | same filing |
| Cerenome senior secured facility | up to $20M | GlobeNewswire, 10 Sep 2026 |
| Cerenome / CNSide royalty | 2.5% of quarterly gross revenue, capped at 2.5% of unpaid note balance | Royalty Agreement, Ex. 10.4, 10 Sep 2026 |
Portfolio Book
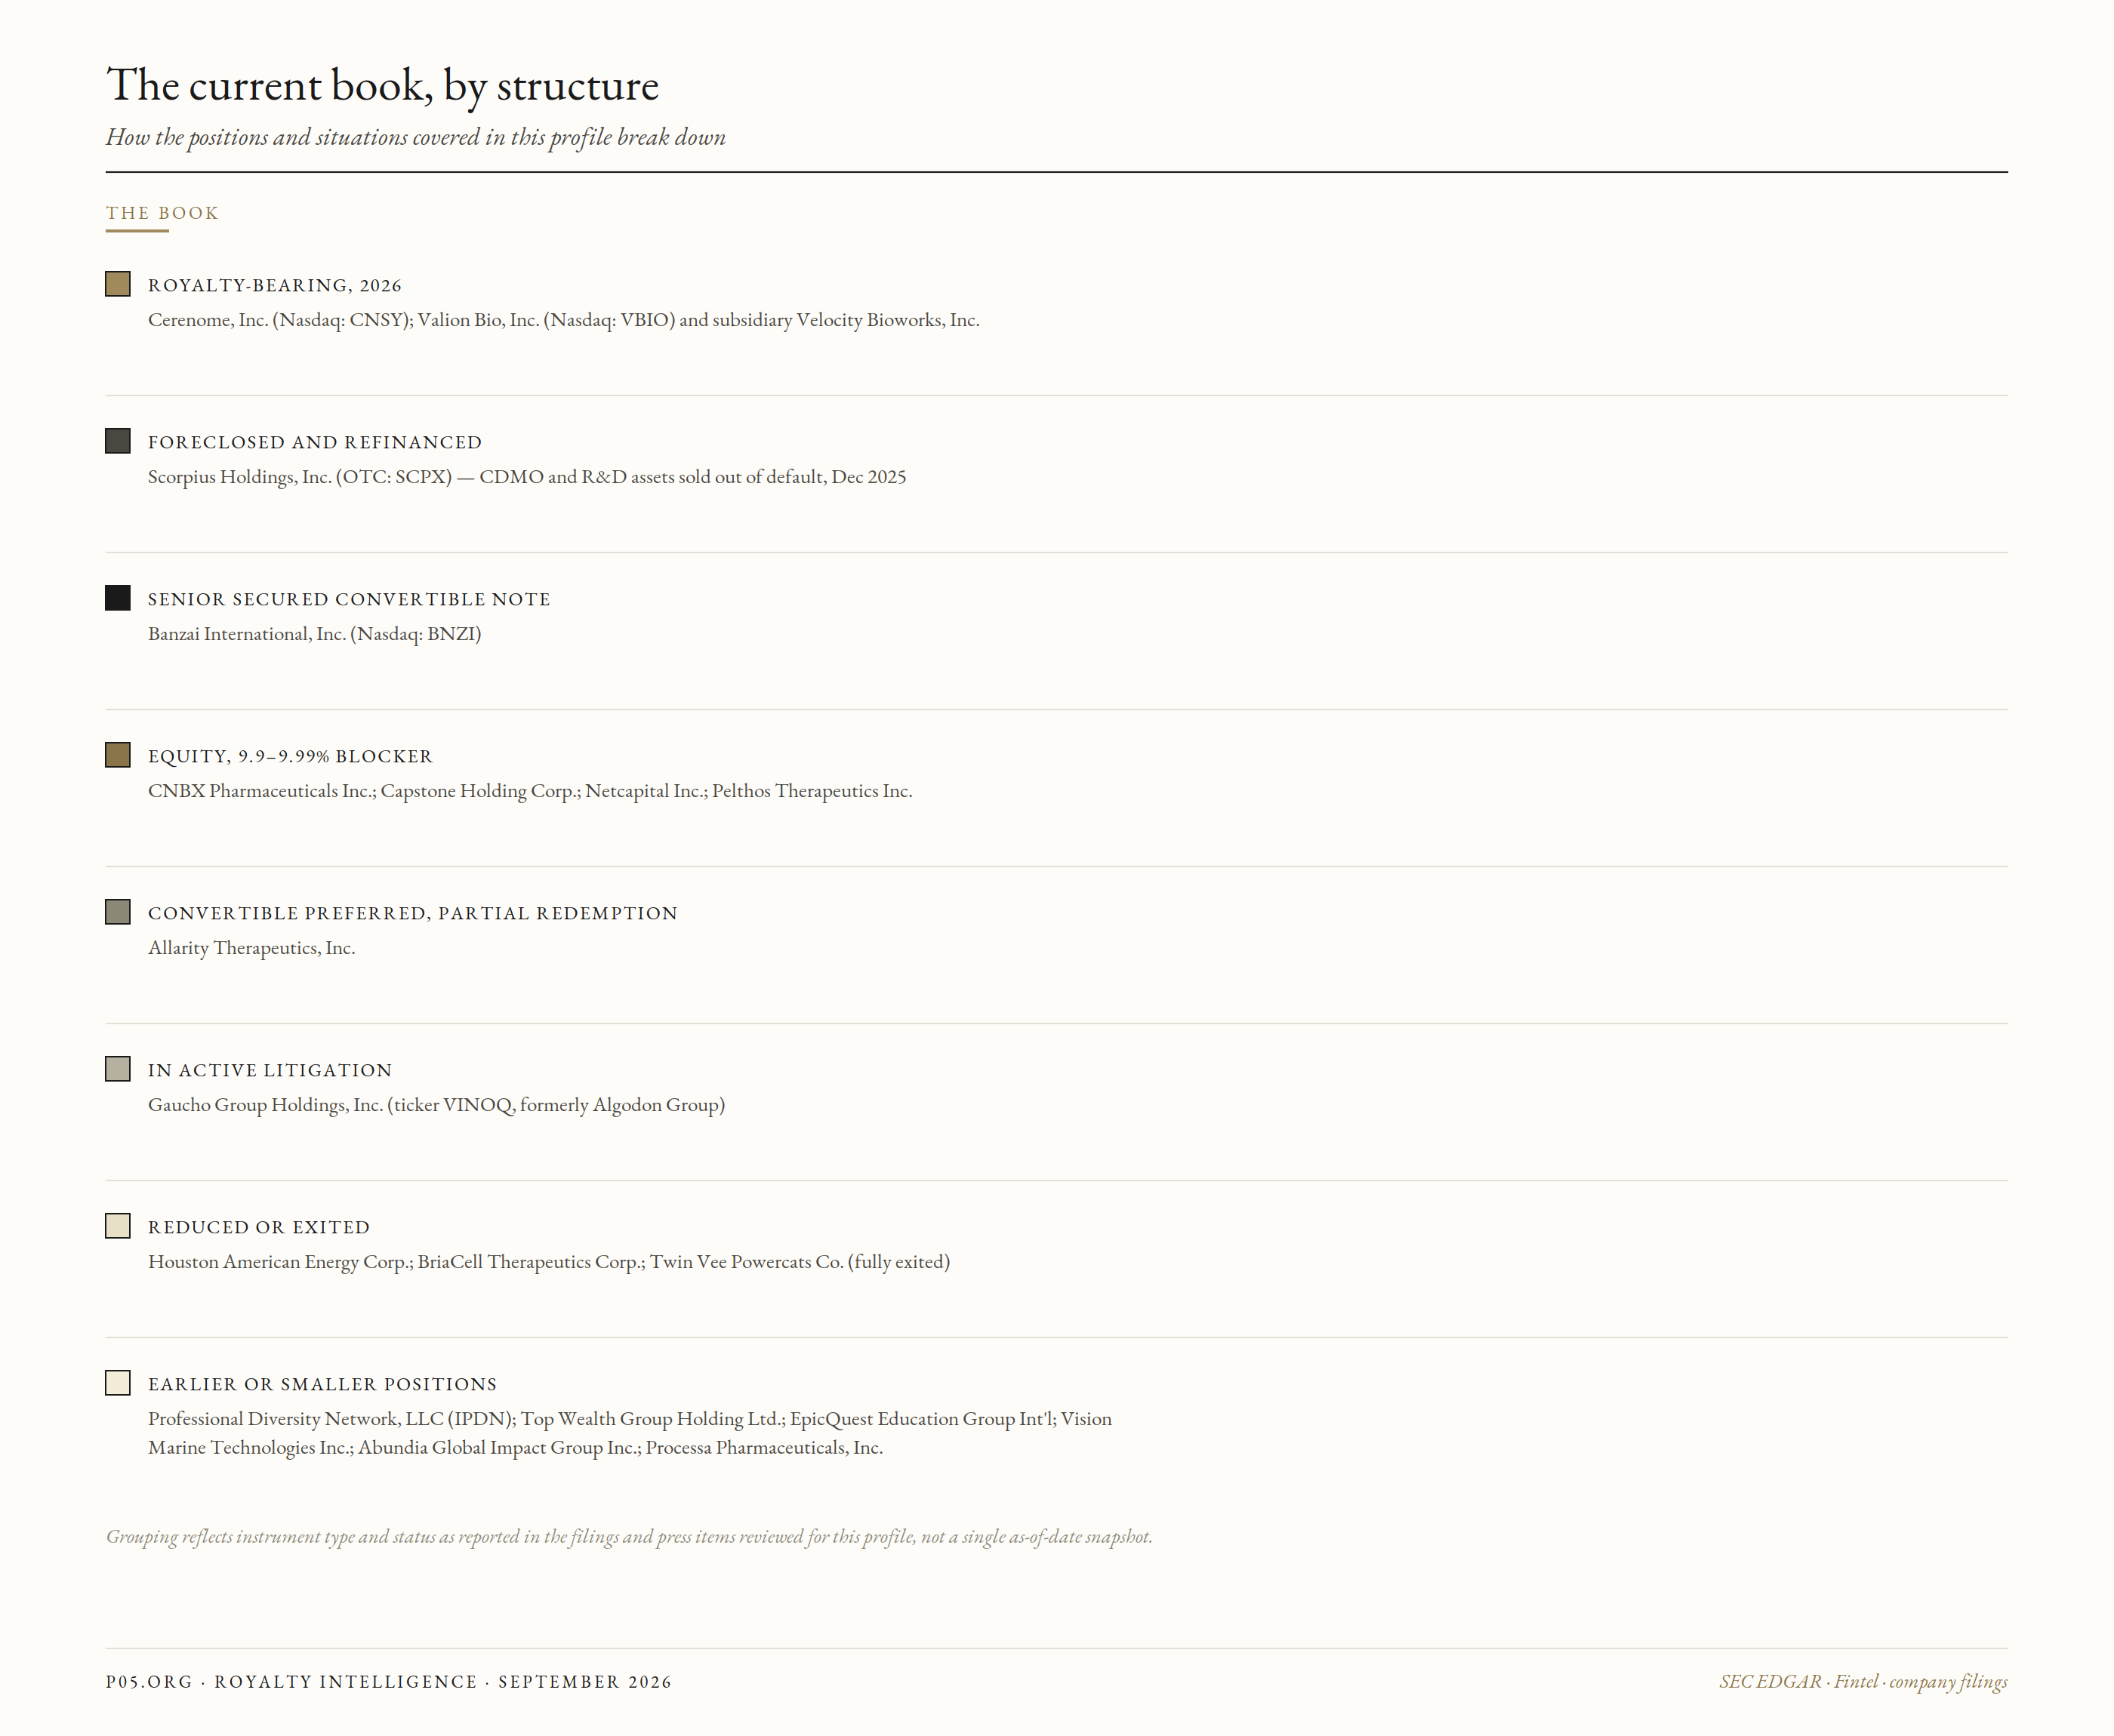
Royalty-bearing financings, 2026: Cerenome, Inc. (Nasdaq: CNSY); Valion Bio, Inc. (Nasdaq: VBIO) and its subsidiary Velocity Bioworks, Inc.
Foreclosed and refinanced: Scorpius Holdings, Inc. (OTC: SCPX), whose CDMO and R&D assets 3i sold out of default in December 2025
Senior secured convertible note position: Banzai International, Inc. (Nasdaq: BNZI)
Equity positions under a 9.9 to 9.99 percent blocker: CNBX Pharmaceuticals Inc.; Capstone Holding Corp.; Netcapital Inc.; Pelthos Therapeutics Inc.
Convertible preferred, with a partial redemption: Allarity Therapeutics, Inc.
In active litigation: Gaucho Group Holdings, Inc. (ticker VINOQ, formerly Algodon Group)
Reduced or exited: Houston American Energy Corp. (down more than 75 percent through May 2025); BriaCell Therapeutics Corp. (down more than 48 percent through May 2025); Twin Vee Powercats Co. (fully exited by August 2025)
Earlier or smaller positions: Professional Diversity Network, LLC (IPDN); Top Wealth Group Holding Limited; EpicQuest Education Group International Limited; Vision Marine Technologies Inc.; Abundia Global Impact Group Inc.; Processa Pharmaceuticals, Inc.
Investors
No LP roster, commitment schedule or fund-size disclosure exists for 3i, LP in any source reviewed. Every deal document describes 3i's capital as its own, and no Form D has been filed under 3i's CIK indicating a capital raise from outside investors under that name. Whether 3i, LP is itself financed by outside capital, and if so by whom, is not addressed in the public record.
Governance and Team
Every filing reviewed carries a single named signatory: Maier Joshua Tarlow, described consistently as Manager of 3i Management LLC, General Partner of 3i, LP. 3i Management's own site names it as manager and general partner of both 3i, LP and Tumim Stone Capital, a separate, more publicly visible equity-line vehicle. No other principal, investment committee member or operating staff appears by name in any SEC filing, court record or press item reviewed for this profile.
Litigation note: 3i's relationship with Gaucho Group Holdings, Inc. has run through three separate dockets. Gaucho sued 3i in Delaware federal court in February 2024, with a memorandum opinion issued 5 November 2024. 3i separately moved for summary judgment in lieu of complaint in New York County Supreme Court over nonpayment under a Senior Secured Convertible Note dated 21 February 2023, with decisions on that motion dated 13 June 2025. 3i and 3i Management also filed a miscellaneous action in the Eastern District of New York on 2 October 2024.
No Form ADV or exempt-reporting-adviser filing for 3i Management LLC has surfaced in this research, and no New York or Delaware corporate registration record beyond the SEC's own address fields has been located.
IP, Royalties and Return Economics
Cerenome and the CNSide Royalty
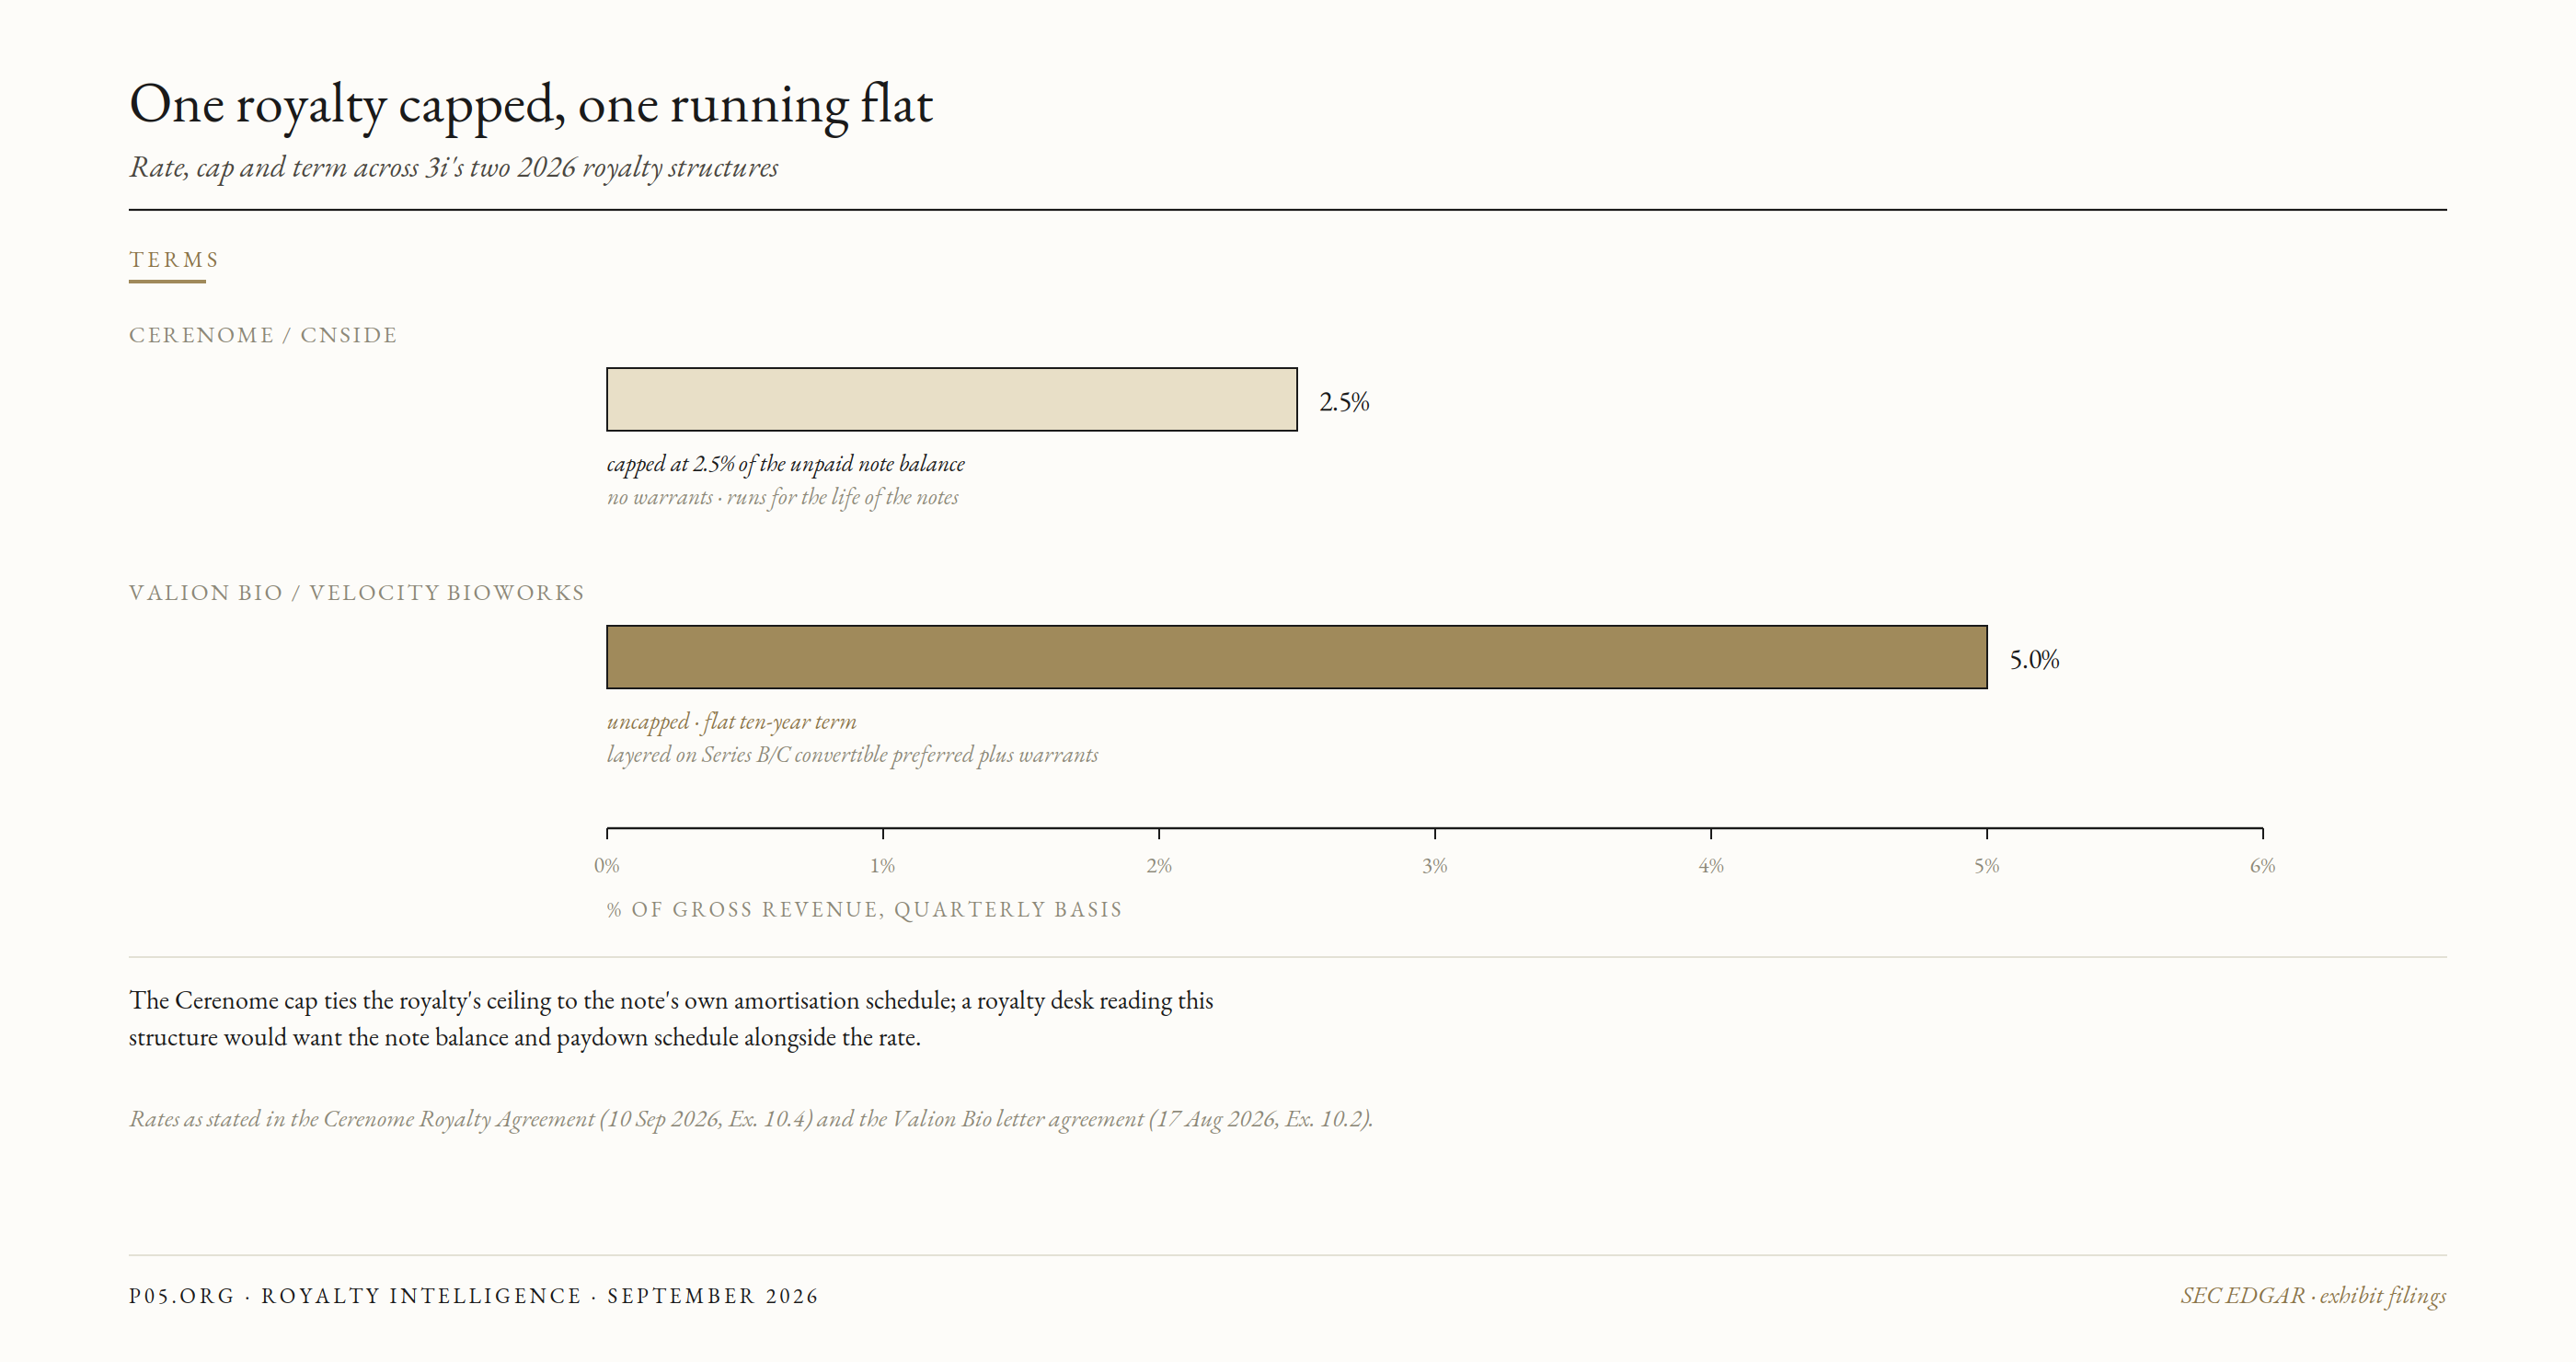
On 10 September 2026 Cerenome, Inc. (formerly Plus Therapeutics until its 3 August 2026 rebrand) closed a senior secured facility with 3i of up to $20M, funded at closing with further tranches tied to milestones. Repayment runs through a Royalty Agreement between Cerenome, CNSide Diagnostics, LLC and 3i: 2.5 percent of CNSide's quarterly gross revenues from third parties, running for the life of the notes, with the quarterly payment capped at 2.5 percent of the unpaid note balance.
CFO Andrew Sims described the facility as designed to be minimally dilutive to stockholders, consistent with a structure that carries no warrant or equity component. CNSide is a cerebrospinal-fluid diagnostic for central nervous system metastases; the company has separately scheduled a CNSide business update call for 30 September 2026. No 13D or 13G by 3i on Cerenome has been filed as of this writing.
The royalty is capped against the loan rather than left open-ended, which ties its ceiling to the note's own amortisation schedule rather than to CNSide's revenue growth. A royalty desk reading this structure would want the note balance and the amortisation schedule alongside the royalty rate, since the cap can bind before the rate does.
Valion Bio, Velocity Bioworks and the Scorpius Foreclosure
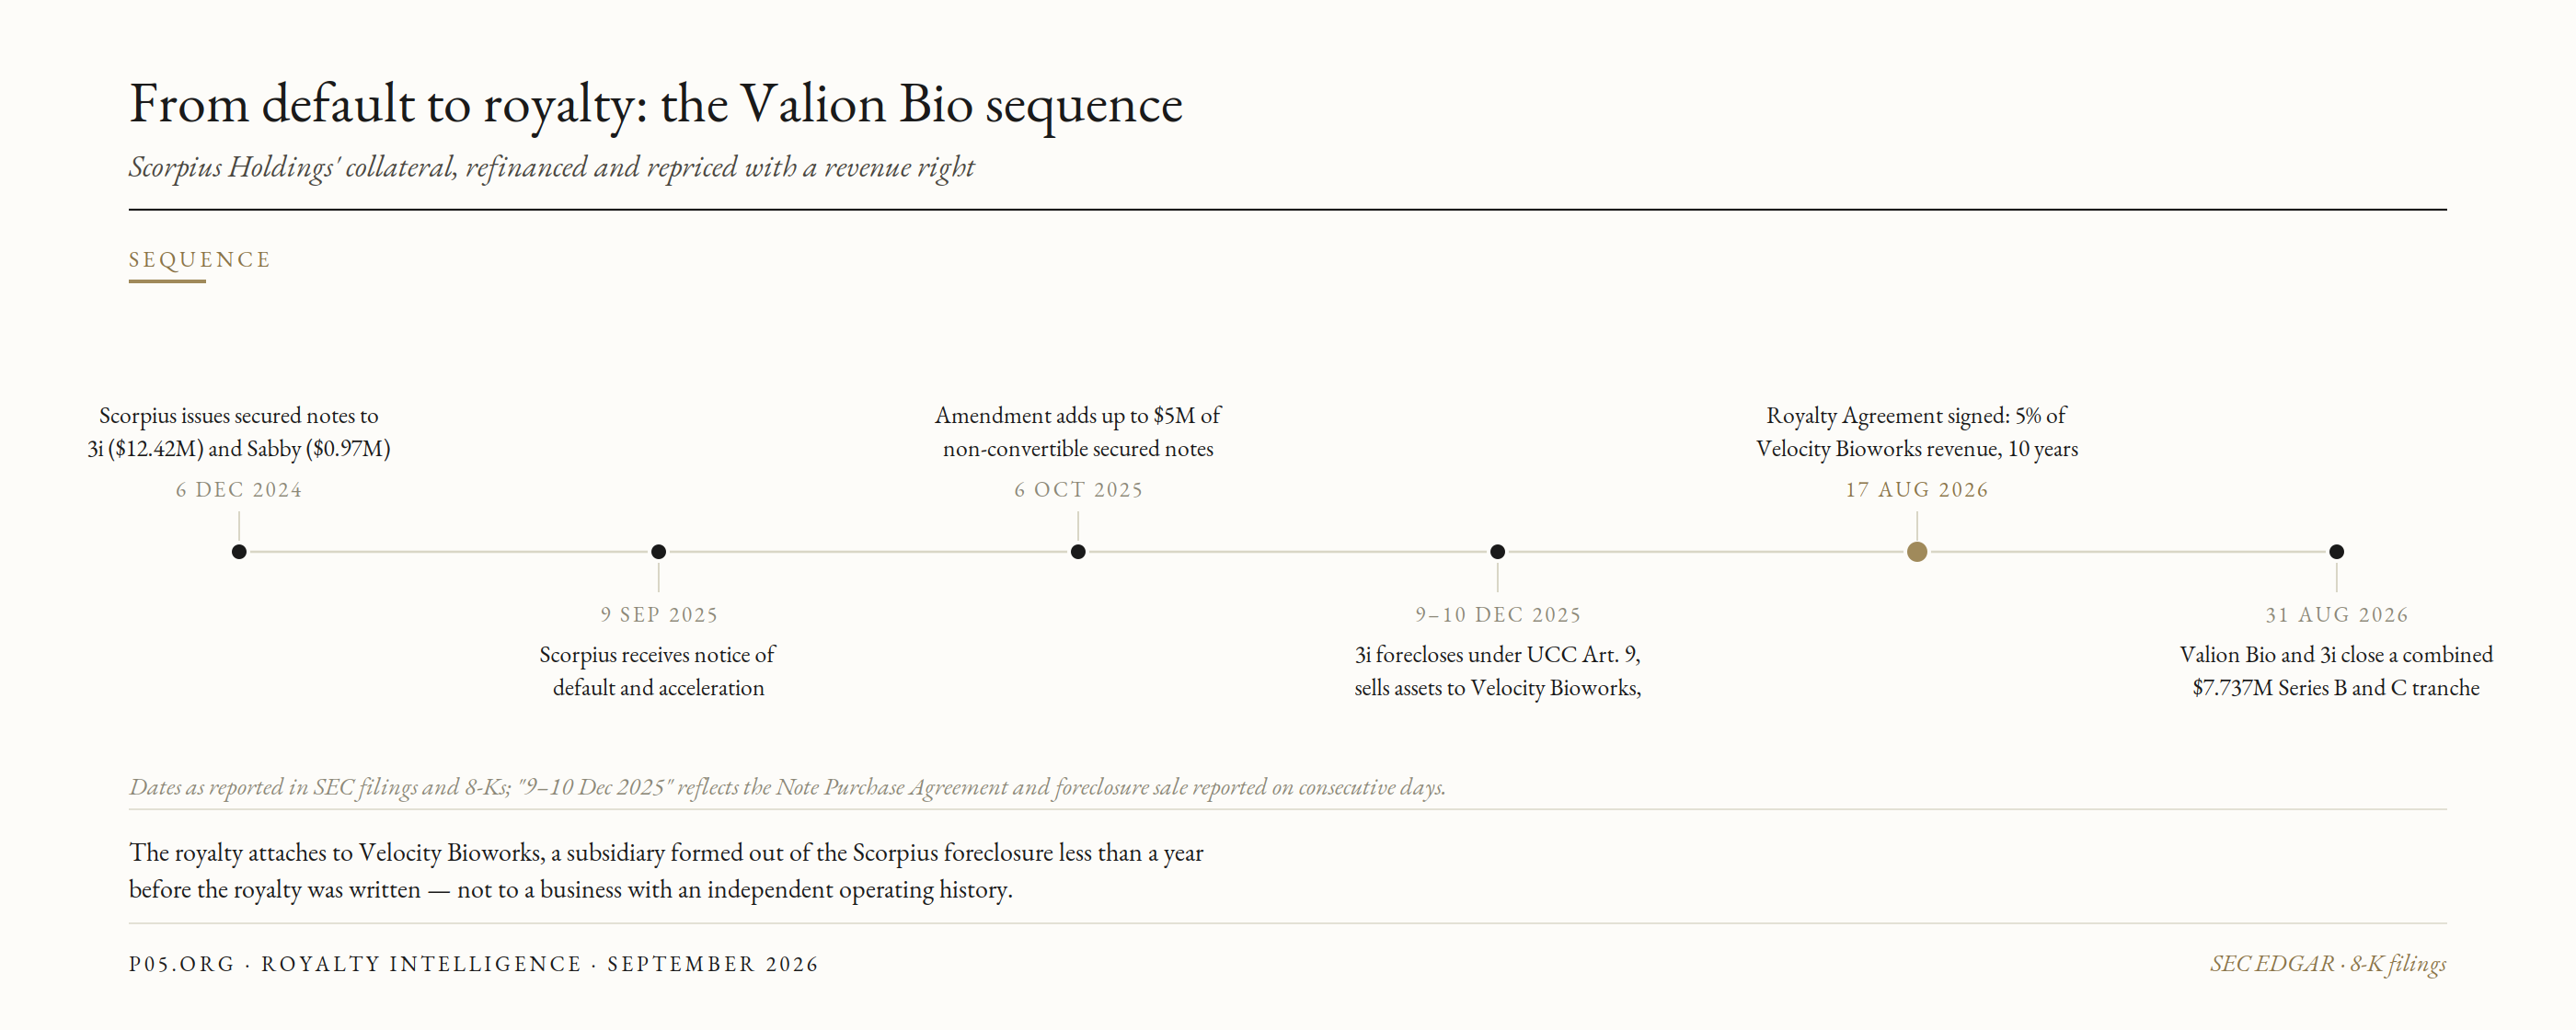
This position traces back through a separate borrower's default. Scorpius Holdings, Inc. had issued senior secured convertible notes to 3i and Sabby Volatility Warrant Master Fund on 6 December 2024 in original principal amounts of $12,416,667 and $972,222. Scorpius received a notice of default and acceleration on 9 September 2025, and an Amendment Agreement dated 6 October 2025 added up to $5M of non-convertible secured promissory notes on top of the existing debt.
3i, acting as collateral agent, ran a foreclosure sale of substantially all of Scorpius's non-cash CDMO and R&D assets under UCC Article 9 on 10 December 2025, for net proceeds of $15,219,552 after fees. The buyer was Velocity Bioworks, Inc., a newly formed subsidiary of Tivic Health Systems, and the Asset Purchase Agreement and Secured Bill of Sale ran between 3i as collateral agent and seller and Velocity Bioworks as buyer, dated the same day the notes were struck.
Tivic funded that purchase with new 3i capital. On 9 December 2025 the company and VBI entered a Note Purchase Agreement for a senior secured convertible note of $16,253,147.10 plus a warrant over 4,553,213 shares, secured over the same assets 3i had just sold out of foreclosure.
The same day, 3i also acquired, by assignment from Helena Global Investment Opportunities, the company's existing Series B Non-Voting Convertible Preferred Purchase Agreement, and negotiated the Series B floor price down to $0.39 a share.
The company, renamed Valion Bio in 2026, drew further Series B and a new $75M Series C Preferred facility from 3i through the year: a $250,000 Series B tranche in mid-June 2026, a $1.5M Series B tranche on 17 August 2026, and a combined $7,737,000 Series B and Series C closing on 31 August 2026.
The 17 August letter agreement carried the royalty term: 3i and the other Series B and C investors receive 5 percent of Velocity Bioworks's gross revenue from third parties for ten years. Each conversion has been reported through a Schedule 13D/A capped at a 9.9 percent blocker, with amendments on 20 August, 31 August and into early September 2026.
The royalty here sits downstream of the foreclosure: the 5 percent right on Velocity Bioworks's gross revenue attaches to a business 3i itself sold out of a defaulted borrower nine months earlier, then refinanced with a new secured note. Any read of the stream has to start from the Scorpius default and asset sale rather than from Velocity Bioworks's own operating history, which barely exists yet in public filings.
Absent Royalties
Banzai International, CNBX Pharmaceuticals, Capstone Holding, Netcapital, Pelthos Therapeutics, Allarity Therapeutics and Gaucho Group Holdings carry none of this: no royalty, revenue-interest or milestone term has surfaced in any of the reviewed contracts, only conversion rights, warrants and, at Gaucho, litigated debt.
Blue Team
- A six-year filing history, running from a December 2020 note to Cannabics Pharmaceuticals through the September 2026 Cerenome facility, across more than eighty Schedule 13D and 13G filings
- A demonstrated capacity to work a defaulted borrower's collateral through to a funded buyer without an external special-servicer relationship: the Scorpius foreclosure, asset sale and same-day refinancing of the buyer all ran through 3i in December 2025
- Consistent use of ownership blockers across equity-linked deals, which caps single-issuer disclosure risk and keeps 3i below the reporting and governance thresholds that would otherwise attach to a controlling stockholder
- A senior secured, first-priority position in several of the reviewed borrowers, including explicit subordination of a later Banzai International lender to 3i's existing debt
- Two royalty-bearing structures now in place within a single month, giving 3i two data points on how a revenue-royalty term prices against a floor-price convertible and against a foreclosure-financed refinancing
Red Team
- No fund size, LP base, AUM, ADV filing or corporate registration record has been found; every fact in this profile is reconstructed from counterparty disclosures rather than from any statement 3i has made about itself beyond the one paragraph on its manager's website
- Active litigation with Gaucho Group Holdings runs on three dockets across two states and a federal circuit; the Delaware securities case shows the relationship has, at least once, moved from default remedy to disputed litigation rather than a negotiated workout
- The Scorpius foreclosure and same-day refinancing of the buyer places 3i on both sides of a single collateral pool within one transaction, concentrating recovery risk in 3i's own assessment of the assets rather than in an arm's-length sale process
- Borrower dilution across the book is substantial by the numbers on record: CNBX Pharmaceuticals' outstanding share count reached 1,225,768,095 by March 2026, and Valion Bio has run through six Schedule 13D amendments in three weeks as conversions land
- Neither royalty has a payment history: both are dated August and September 2026, and the Cerenome cap at 2.5 percent of the unpaid note balance means the royalty could pay very little if CNSide's revenue growth outpaces the loan's amortisation schedule
- Reporting is entirely counterparty-driven; gaps in one borrower's filings become gaps in this profile
Implications for the Pharmaceutical Royalty and Biotech Capital Markets
A royalty term can now arrive as a lender's own pricing mechanism rather than as an acquired stream. Both Cerenome and Valion Bio show 3i writing a percentage-of-revenue right into its own financing paper, not buying one from an originator or a prior holder. Neither borrower had a royalty on the cap table before 3i's facility; both do now.
The Cerenome structure is the more portable template. A royalty capped against the note balance, inside a facility with no warrants, on a company that already carries a commercial diagnostic product and a public listing, gives a royalty desk a single instrument to underwrite: the note, its amortisation schedule, and the cap that ties the royalty's ceiling to the loan rather than to CNSide's own revenue trajectory.
The Valion Bio structure is harder to generalise from, because it grew out of a foreclosure 3i itself conducted. The royalty attaches to Velocity Bioworks, a business that existed for less than a year before the royalty was written, on assets 3i sold to it out of a defaulted borrower and then refinanced. Any underwrite of that stream has to start from the Scorpius default rather than from an operating history that barely exists in public filings yet.
Neither deal makes 3i a counterparty a royalty fund would meet as a seller. Nothing in the record suggests 3i originates, trades or intends to acquire royalties from other parties. The relevance is comparative: two royalty-repayment terms have appeared inside microcap structured-finance deals within three weeks of each other, from the same lender, in unrelated borrowers, worth tracking as a data point on where else the mechanic might turn up.
Recent Developments
- Cerenome, Inc. closes a $20M royalty-repayment facility with 3i, LP on 10 September 2026
- Valion Bio and 3i close a combined $7,737,000 Series B and Series C tranche on 31 August 2026
- Valion Bio, 3i and the other preferred investors sign a Royalty Agreement for 5 percent of Velocity Bioworks's gross revenue on 17 August 2026, alongside a $1.5M Series B tranche
- CNBX Pharmaceuticals issues 100,000,000 shares to 3i on note conversion on 17 March 2026
- Banzai International closes a fourth 3i note for $2,333,333 on 13 February 2026
- 3i, as collateral agent, forecloses on Scorpius Holdings' CDMO assets and sells them to a new Valion Bio subsidiary, funded by a new $16.25M 3i note, on 9 to 10 December 2025
- Capstone Holding Corp. signs a Securities Purchase Agreement with 3i on 29 July 2025
- Scorpius Holdings receives a notice of default on its 3i and Sabby secured notes on 9 September 2025
- Banzai International closes its initial 3i note facility, $11.0M in aggregate original principal, on 27 June 2025
- No purchased or acquired royalty transaction, as distinct from a royalty term written into 3i's own lending, has been identified anywhere in the record
Financial History and Recent Developments
| Date | Event |
|---|---|
| 16 Dec 2020 | 3i funds Cannabics Pharmaceuticals (now CNBX) with a $2.5M senior secured convertible note, the earliest documented 3i deal |
| 25 Jan 2021 | 3i, LP's earliest SEC beneficial-ownership filing under its own CIK |
| 20 May 2021 | Allarity Therapeutics Securities Purchase Agreement issues Series A Convertible Preferred Stock and warrants to 3i |
| 21 Feb 2023 | Gaucho Group Holdings issues a Senior Secured Convertible Note to 3i, later the subject of litigation |
| 6 Mar 2023 | 3i files its original Schedule 13G on CNBX Pharmaceuticals |
| 6 Jun 2023 | 3i and Allarity sign a Limited Waiver and Amendment Agreement enabling a partial Series A redemption |
| 16 Feb 2024 | Gaucho Group Holdings sues 3i, LP in Delaware federal court |
| 2 Oct 2024 | 3i and 3i Management file a miscellaneous action against Gaucho in the Eastern District of New York |
| 5 Nov 2024 | Memorandum opinion issued in Gaucho Group Holdings v. 3i, LP, District of Delaware |
| 6 Dec 2024 | Scorpius Holdings issues senior secured convertible notes to 3i ($12,416,667) and Sabby ($972,222) |
| 13 Jun 2025 | New York County Supreme Court rules on motions in 3i's summary-judgment action against Gaucho |
| 27 Jun 2025 | Banzai International closes its initial 3i note facility, $11.0M in aggregate original principal |
| 29 Jul 2025 | Capstone Holding Corp. signs a Securities Purchase Agreement with 3i |
| 9 Sep 2025 | Scorpius Holdings receives a notice of default on its 3i and Sabby secured notes |
| 6 Oct 2025 | Scorpius Amendment Agreement adds up to $5M of non-convertible secured notes |
| 9 to 10 Dec 2025 | 3i forecloses on Scorpius's CDMO assets, sells them to a new Valion Bio subsidiary for net proceeds of $15,219,552, and funds the buyer with a new $16.25M secured note; 3i also takes assignment of Valion Bio's Series B Preferred Purchase Agreement from Helena Global Investment Opportunities |
| 13 Feb 2026 | Banzai International closes a fourth 3i note, $2,333,333 |
| 17 Mar 2026 | CNBX Pharmaceuticals issues 100,000,000 shares to 3i on note conversion |
| Jun 2026 | Valion Bio draws a further $250,000 Series B tranche from 3i |
| 17 Aug 2026 | Valion Bio, 3i and other preferred investors sign a Royalty Agreement for 5 percent of Velocity Bioworks's gross revenue for ten years, alongside a $1.5M Series B tranche |
| 31 Aug 2026 | Valion Bio and 3i close a combined $7,737,000 Series B and Series C tranche |
| 2 to 4 Sep 2026 | Further Valion Bio Schedule 13D/A and 13G/A amendments as conversions continue |
| 10 Sep 2026 | Cerenome, Inc. closes a $20M senior secured facility with 3i, repaid through a 2.5 percent CNSide revenue royalty |
Conclusion
3i, LP is a single-signatory, six-year-old microcap structured lender with no disclosed fund size, no LP roster and no regulatory registration found under its own or its manager's name. Its deal paper runs to senior secured convertible notes, non-voting convertible preferred stock, warrants, and, at Scorpius Holdings, a UCC Article 9 foreclosure that 3i itself conducted and then refinanced through a new borrower the same day.
It also holds two revenue royalties, one capped against a loan's own amortisation at Cerenome, one running a flat ten years on a business it helped create out of that foreclosure at Valion Bio. Neither is a stream this publication's usual counterparties would recognise as an acquisition target. Both are evidence that the royalty mechanic has started to appear inside microcap lending on the lender's own terms, and worth watching for where it turns up next.
All information in this report was accurate as of the research date and is derived from publicly available sources including court opinions, regulatory guidance, academic literature, SEC filings, and financial news reporting. Information may have changed since publication. This content is for informational purposes only and does not constitute investment, legal, or financial advice. The author is not a lawyer or financial adviser.