Fund of the Week: Oaktree Capital Management
On 21 October a bankruptcy judge in Delaware is due to hear the sale of BioXcel Therapeutics, the maker of Igalmi. Teva has offered $57.5M in cash. The two lenders paying for the case, Oaktree Capital Management and Qatar Investment Authority, have committed up to $77.25M to it, and most of that sum is old debt carried into a new loan.
In April 2022 the same lenders promised BioXcel up to $260M. Part of it was a revenue interest, a share of Igalmi's American sales capped at 1.75 times the money advanced. That interest will not be before the court. It was terminated in December 2023, and the $30M paid for it became a term loan.
Oaktree has held four such interests since 2022, and three no longer exist as royalties. Impel Pharmaceuticals had its interest exchanged into loans before it went bankrupt. Verona Pharma bought its interest back after nine months at 1.17 times the funded amount. The fourth, a purchase of Athenex's Klisyri royalties made with Sagard, appears to survive as a $14.0M loan to ATNX SPV, LLC in Oaktree's listed lending fund.
The record suggests that a revenue interest held by the borrower's own senior lender works as a loan with a coupon tied to sales, and that it is treated as a loan when trouble comes.
At a Glance
- What it is: a senior secured lender to commercial-stage and near-commercial biopharma, medical device and healthcare services companies, which on four occasions has paired or supplemented its loan with a revenue interest
- Manager: Oaktree Capital Management, L.P., founded in 1995 and headquartered at 333 South Grand Avenue, Los Angeles
- Ownership: Brookfield acquired about 61.2 percent on 30 September 2019, agreed on 13 October 2025 to buy the remaining 26 percent or so for about $3B, and announced completion on 3 August 2026
- Assets under management: about $223B at 31 December 2025
- Dedicated fund: Oaktree Life Sciences Lending Fund, which closed with commitments in excess of $2.3B in June 2023
- Newer vehicle: Oaktree Life Sciences Income Fund, L.P., which filed a Form D on 29 January 2025 with no sales recorded at filing; no target or close has been published
- Stated track record: $6.2B across 54 investments through 31 December 2025, with no realised losses, from more than 996 opportunities reviewed
- Portfolio managers: Aman Kumar and Armen Panossian
- Public reporting vehicles: Oaktree Specialty Lending Corporation and Oaktree Strategic Credit Fund, which hold slices of the same loans
- Royalty interests written or bought, 2022 to 2024: Impel, BioXcel, Athenex (Klisyri) and Verona; no new one has been identified in 2025 or 2026
A Note on Scope
Oaktree manages about $223B, and almost none of it has anything to do with royalties. Its other strategies are left out here. So is Oaktree Acquisition Corp. III Life Sciences, a blank-cheque company formed in June 2024 that had named no target by its 2025 annual report. That report is cited below for one reason: it carries the latest public account of the lending team's record.
The private fund publishes no portfolio and no performance. The deal terms in this profile come from borrowers' filings. The position sizes and valuations come from two business development companies (BDCs), which are regulated lending funds that must publish every holding each quarter. Each BDC holds only a slice of a loan, so its dollar figures understate Oaktree's whole position.
OMERS Life Sciences, Oaktree's partner at Verona, was profiled in an earlier issue.
Investment Thesis and Mandate
Oaktree began lending to drug and device makers in 2013. In April 2021 Armen Panossian and Aman Kumar set out the case for it in a paper on life sciences direct lending. Their team, they wrote, had worked on more than 100 debt and royalty financings in healthcare. A lender to a company whose value rests on one drug could "insert terms that limit the impact of binary risks".
The deal documents show what those terms are. Money is released in tranches, and the later ones fund only when a regulator approves the product or sales pass a threshold. The borrower must keep a minimum of cash. It pays a fee to leave, and it usually hands over warrants.
A dedicated fund followed. When it closed in June 2023, Bloomberg reported an average investment of $75M to $200M and a ceiling of 25 percent on the ratio of loan to company value at the outset. Nineteen deals in 20 went to companies with no private equity owner. The product was described as non-dilutive capital, including structured debt and royalties, and the team as 11 people in New York, Los Angeles and London.
By the end of 2025 the book had grown to 54 investments. American companies took 64 percent of them and European ones 31 percent. About three-quarters were in biopharma. Fewer than 5.4 percent of the opportunities the team reviewed reached a final round.
Royalties are a small part of this. No Oaktree source reviewed uses the term synthetic royalty. Gibson Dunn's 2026 survey of the royalty market lists the firm once, as OMERS's co-investor on Verona, and leaves it out of the table of buyers.
How Capital Enters and Returns
The money comes from several vehicles. The fund itself is a set of parallel partnerships. Form D filings from 2021 and 2022 show the Cayman main fund with $164.5M sold to 37 investors, a feeder, and two parallel vehicles, the larger of which had sold about $431M to 11 investors. None was amended after November 2022, so the filings stop well short of the final $2.3B. A co-investment application filed with the SEC in July 2025 adds Luxembourg partnerships and the newer Income Fund to the vehicles that may invest beside the BDCs.
Oaktree also spreads each loan across accounts it runs for single clients. The waiver signed by the Klisyri purchasers in August 2022 lists more than a dozen Oaktree entities on one transaction. Among them are Oaktree-TCDRS Strategic Credit, LLC, Oaktree-Minn Strategic Credit, LLC, INPRS Strategic Credit Holdings, LLC and Oaktree Specialty Lending Corporation.
What goes out is a first-lien term loan of five or six years, on which the borrower pays interest only. Verona's 2024 facility carried a fixed 11.00 percent and a 2.50 percent exit fee, with a penalty for early repayment that fell from 7 percent in the first year to 1 percent in the fourth. Aquestive's 2026 loan floats at 6.25 percentage points over the three-month SOFR benchmark, with warrants worth 1.75 percent of each tranche. One Oaktree entity, Oaktree Fund Administration, LLC, is agent on all of them.
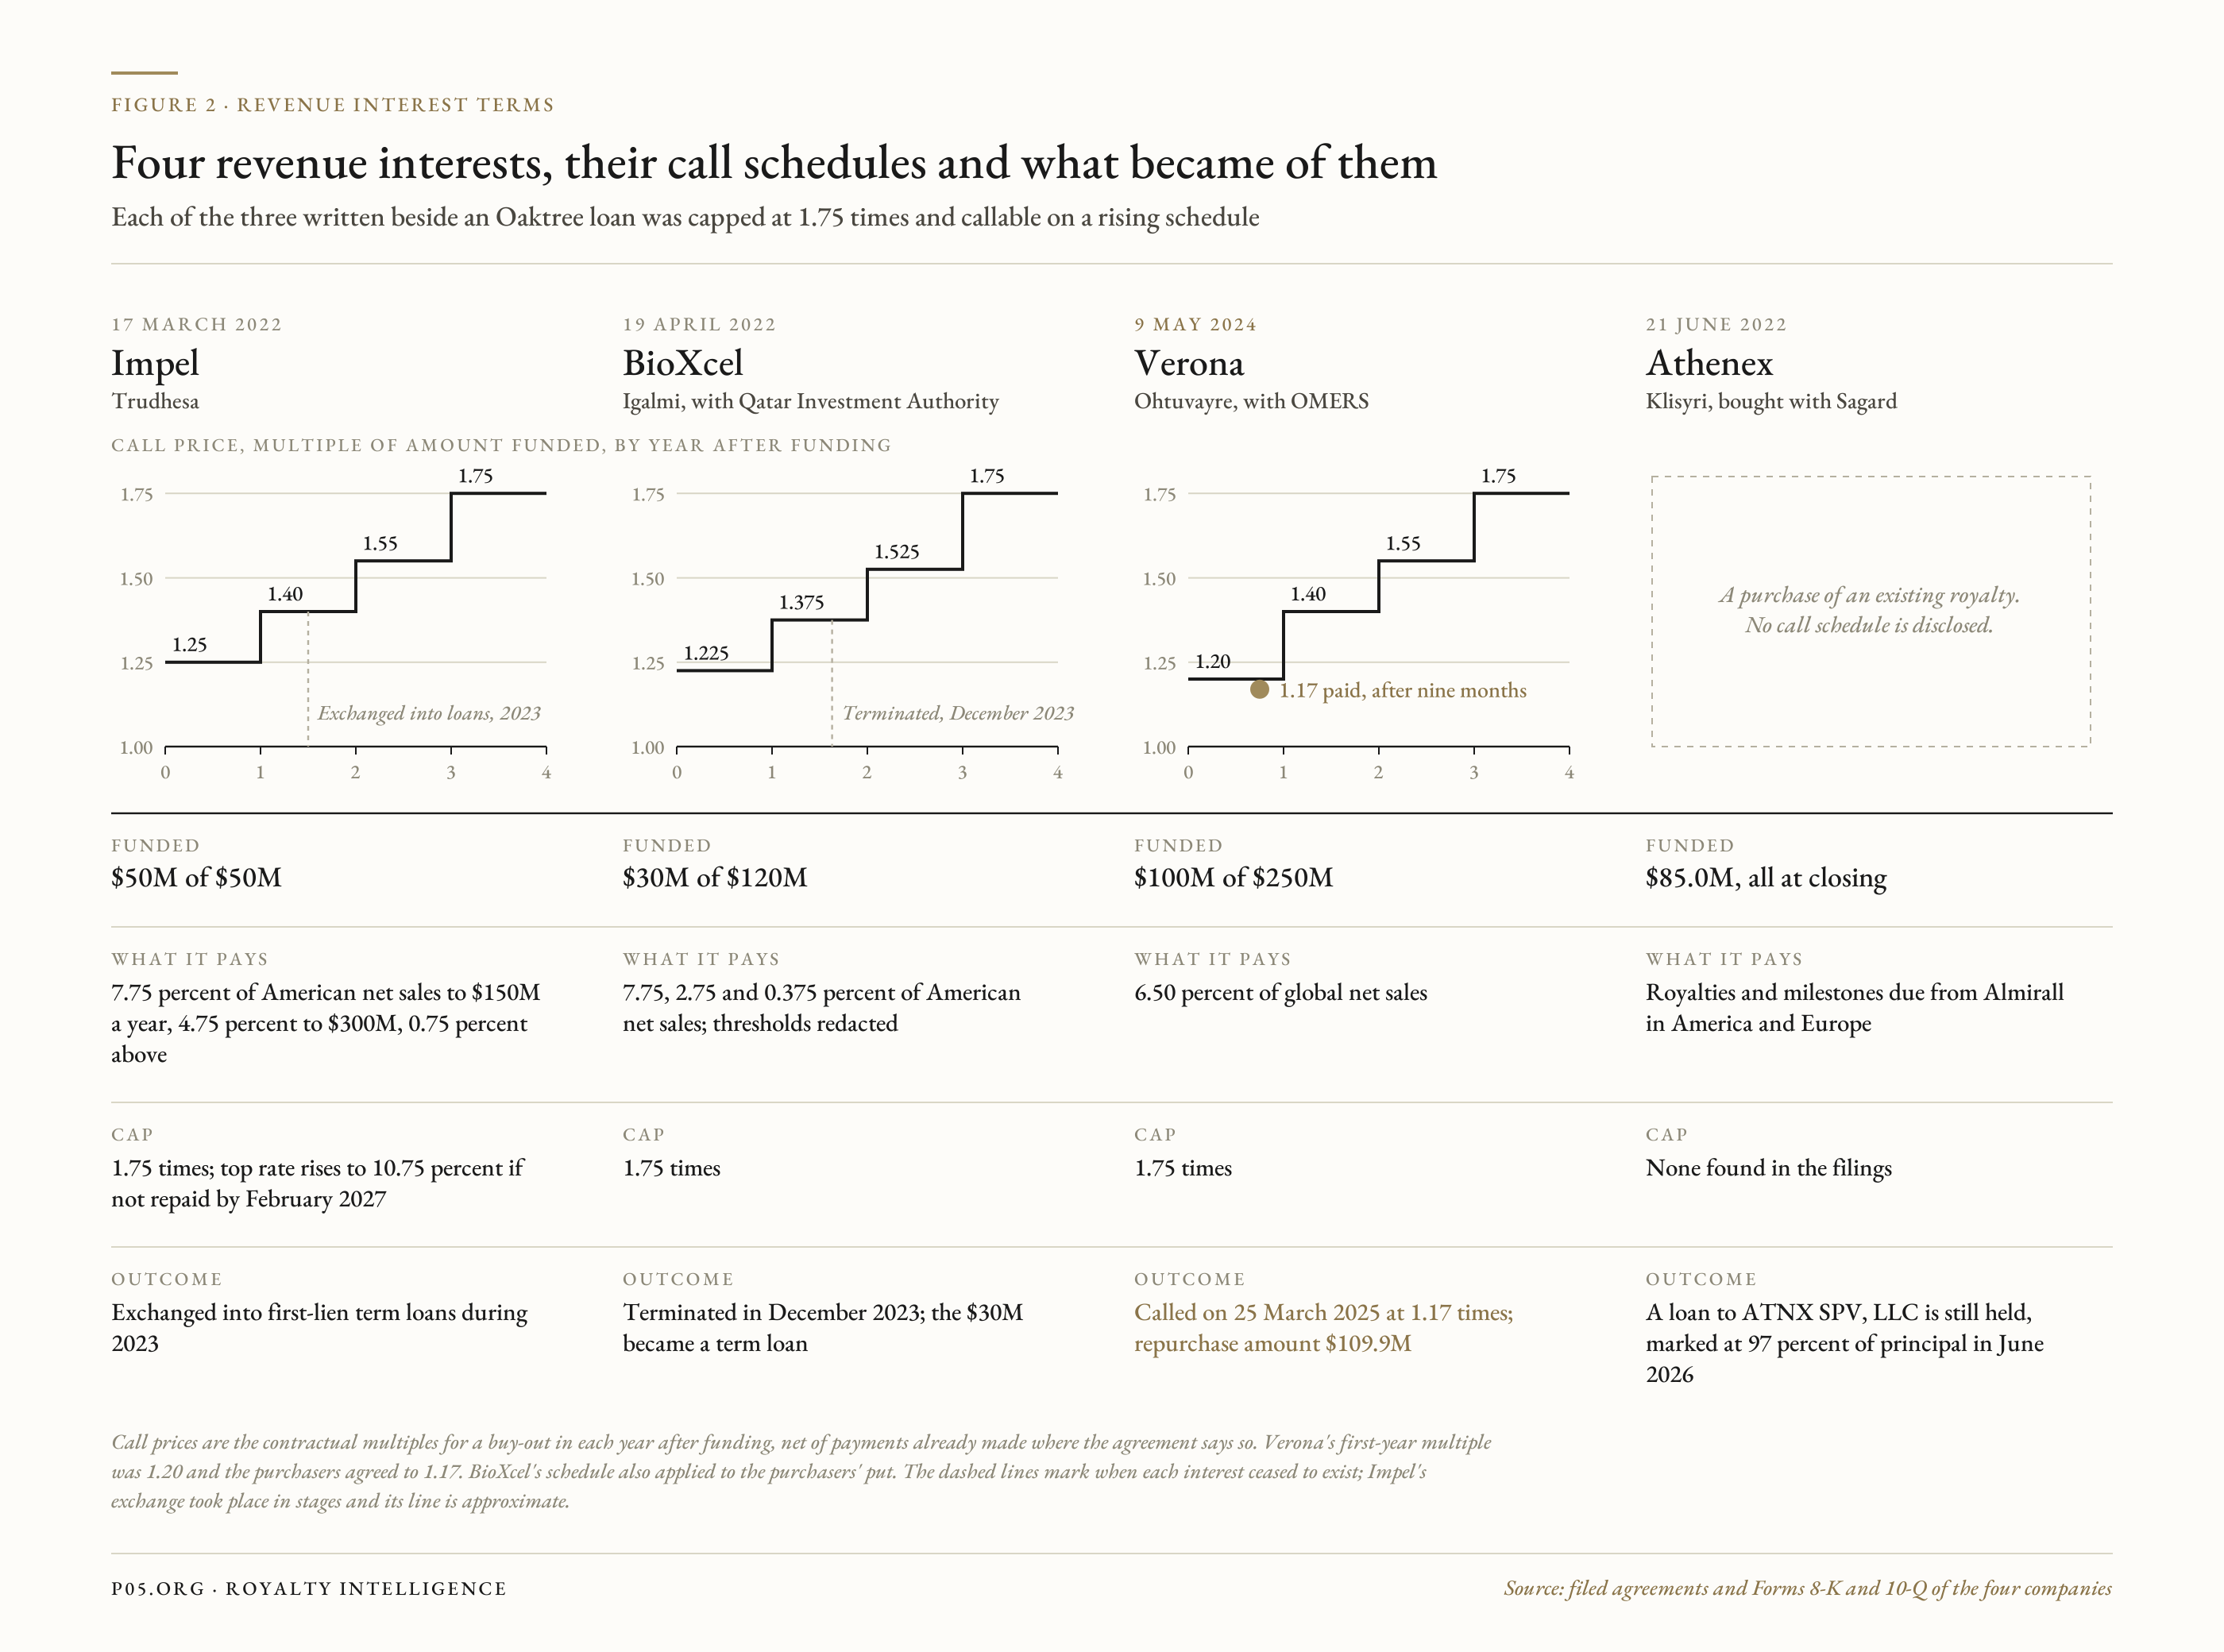
Where a revenue interest exists it sits beside the loan as a second contract, with the same agent and an intercreditor agreement between the two. Each of the three that Oaktree wrote was capped at 1.75 times the amount funded. Each could be bought back at a price that climbed to the cap over three years.
Most borrowers repay by refinancing or by being bought. Seres paid about $128.0M on 30 September 2024 to retire $110.0M of principal, a sum that included about $12.5M for repaying early. Four borrowers have instead filed for Chapter 11. In three of those cases Oaktree financed the bankruptcy or bid its debt for the assets.
Financial Profile and Assets
| Item | Amount | Source and Date |
|---|---|---|
| Oaktree assets under management | about $223B | OACC 10-K, 31 Dec 2025 |
| Life sciences commitments since 2013 | about $6.2B across 54 investments | same filing, 31 Dec 2025 |
| Oaktree Life Sciences Lending Fund, final close | in excess of $2.3B | Simpson Thacher, Jun 2023 |
| Verona Pharma facility, aggregate | up to $650M ($400M loans, $250M revenue interest) | Verona release, 9 May 2024 |
| Verona revenue interest repurchase | $109.9M on $100M funded | 10-Q, 30 Jun 2025 |
| BioXcel facility, aggregate | up to $260M; $100M funded | BioXcel release, 19 Apr 2022 |
| BioXcel debtor-in-possession loan | up to $77.25M ($19M new money, $58.25M roll-up) | 8-K, 27 Aug 2026 |
| Impel loan and revenue interest | $50M and $50M | 8-K, 17 Mar 2022 |
| Klisyri revenue interest purchase (with Sagard) | $85.0M | 8-K, 21 Jun 2022 |
| Establishment Labs facility | $300M; $265M funded | company release, 30 Apr 2026 |
| Aquestive facility | $150M; $55M funded | 8-K, 12 May 2026 |
| OXB facility | up to $125M; $60M funded | OXB release, 1 Aug 2025 |
| Oaktree Specialty Lending, investments at fair value | $2.74B | 10-Q, 30 Jun 2026 |
| ATNX SPV, LLC at Oaktree Specialty Lending | $14.4M principal, $14.0M fair value | same filing |
| BioXcel term loans at Oaktree Specialty Lending | $9.5M principal, $8.3M fair value | same filing |
Portfolio Book
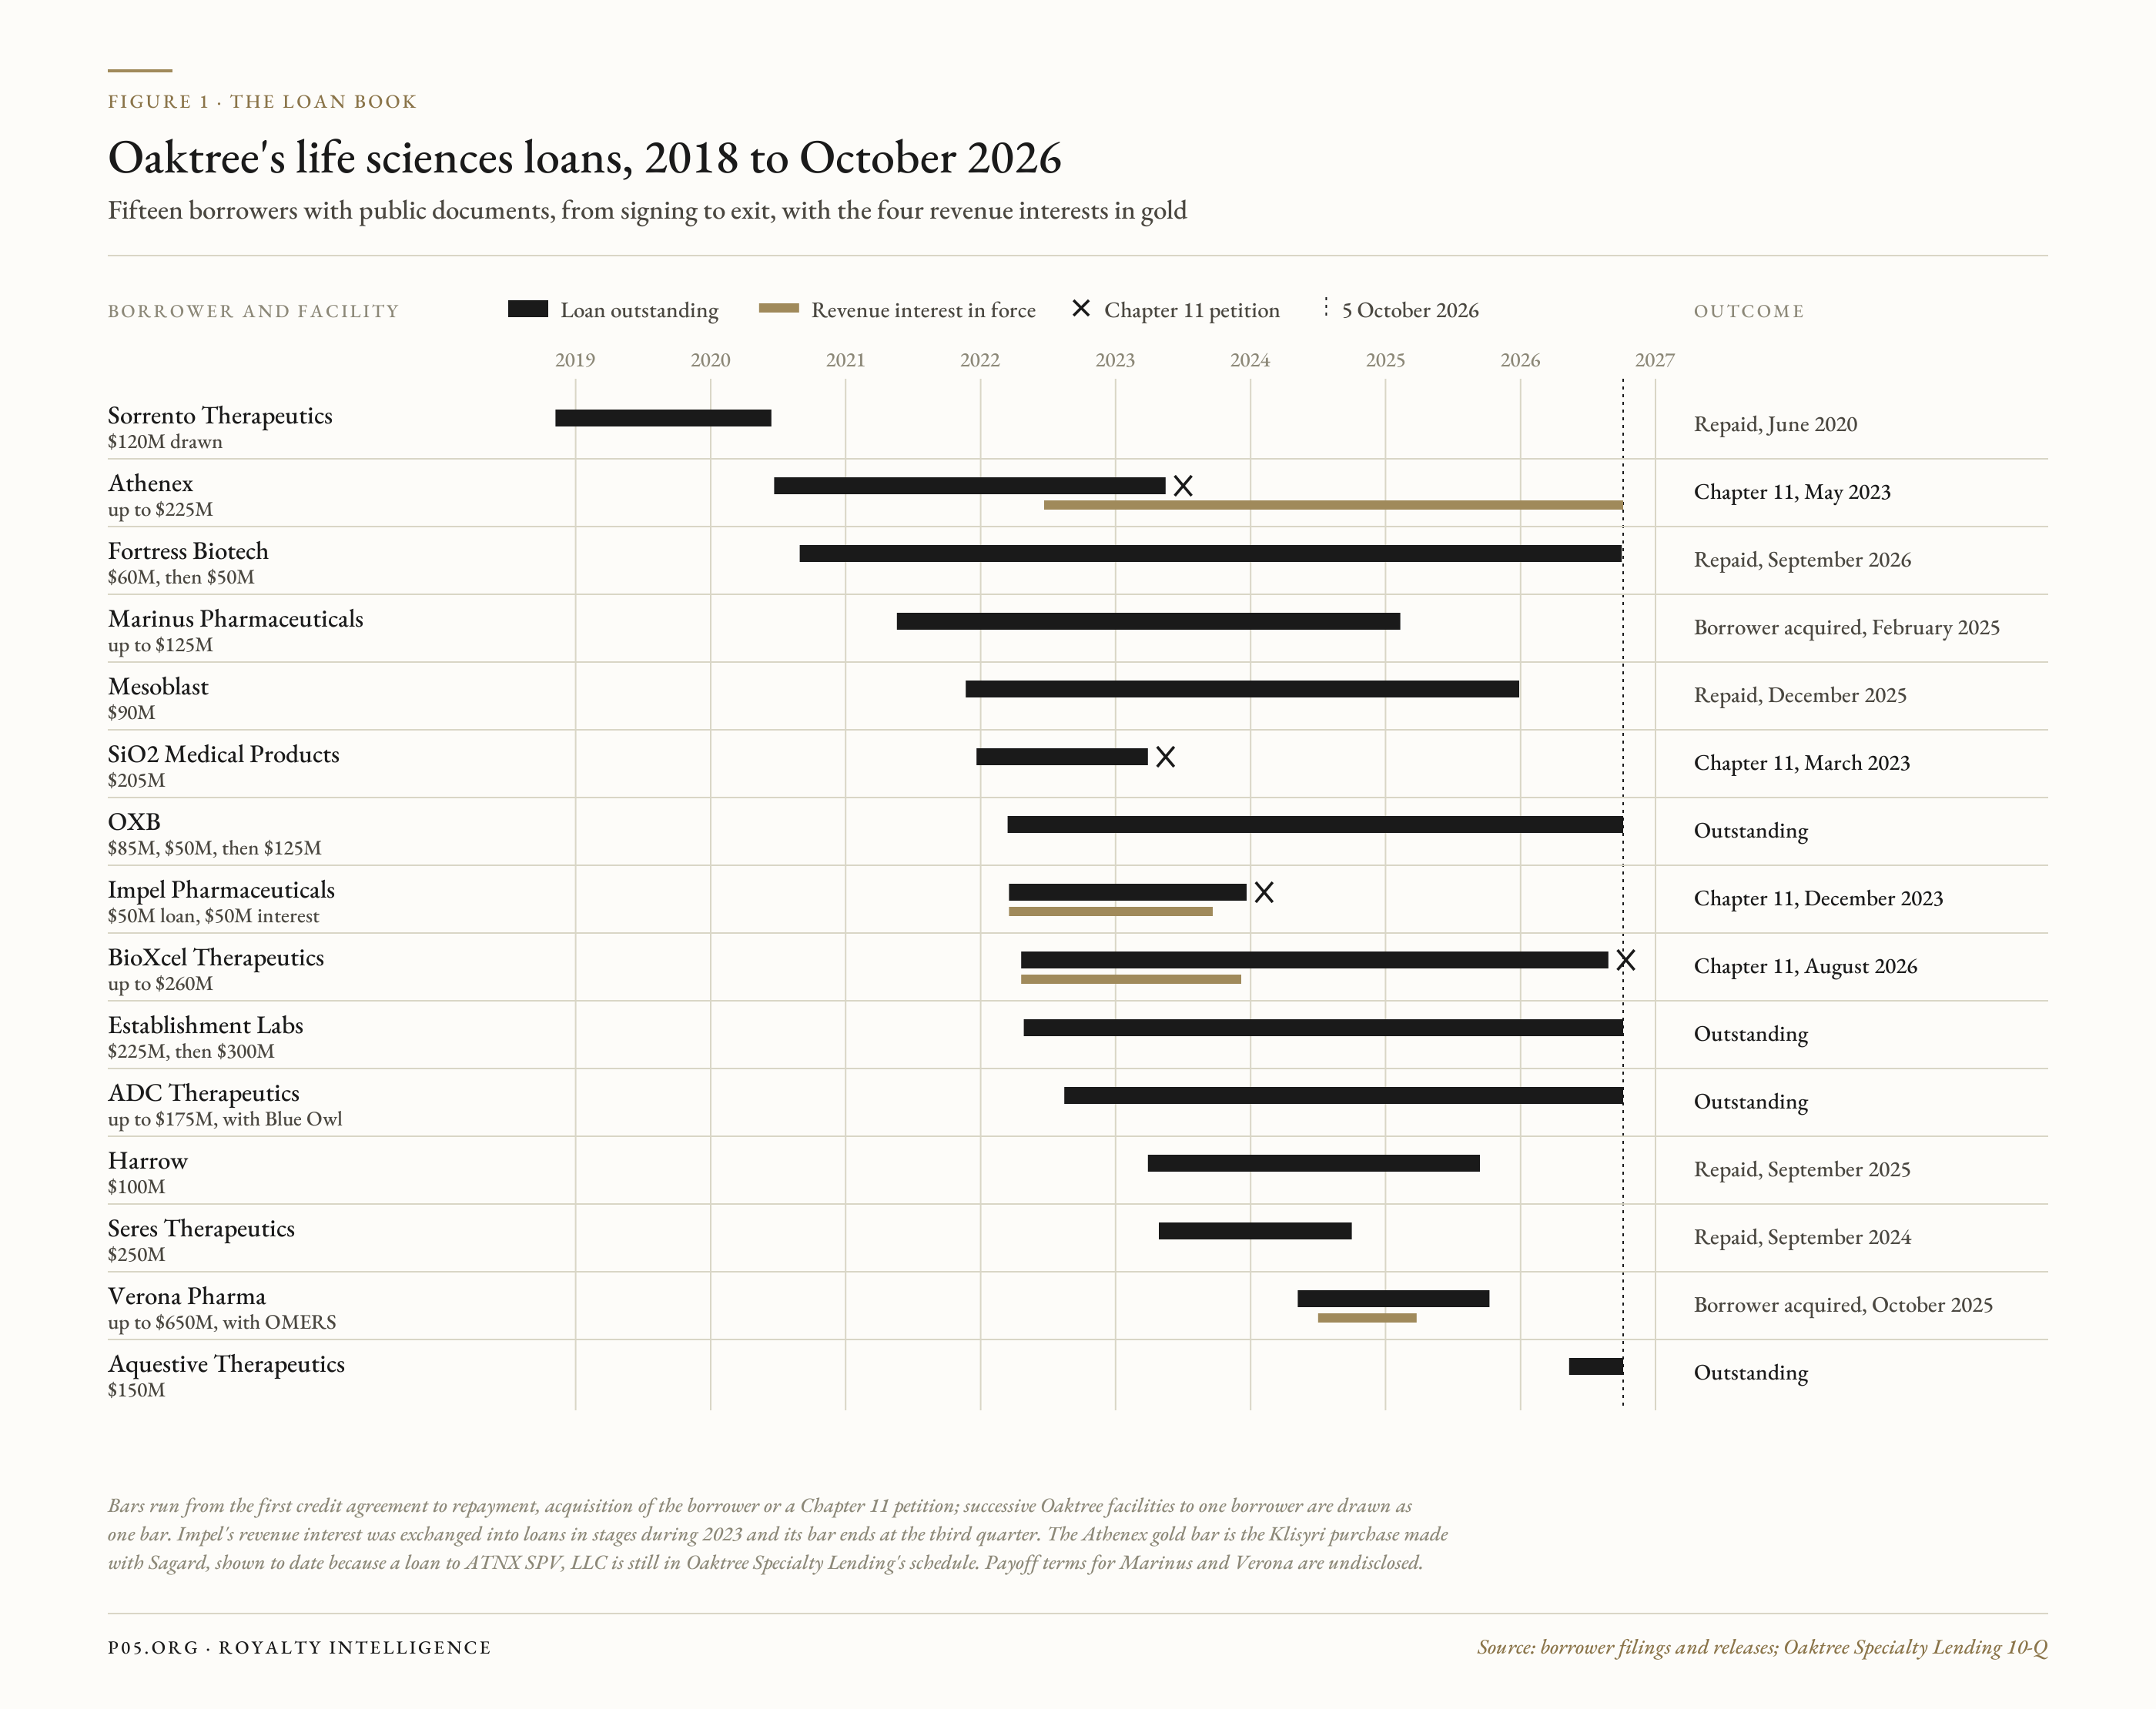
Revenue interests, with outcome: Verona Pharma (bought out, March 2025); BioXcel Therapeutics (converted to term loan, December 2023); Impel Pharmaceuticals (exchanged into term loans, 2023); Athenex, for Klisyri royalties under the Almirall licence (held through ATNX SPV, LLC)
Loans outstanding: Establishment Labs Holdings (Nasdaq: ESTA); Aquestive Therapeutics (Nasdaq: AQST); ADC Therapeutics (NYSE: ADCT), with Blue Owl; OXB (LSE: OXB); BioXcel Therapeutics, now as debtor-in-possession lender
Repaid or refinanced, 2024 to 2026: Fortress Biotech (September 2026); Mesoblast (December 2025); Harrow (September 2025); Seres Therapeutics (September 2024); scPharmaceuticals (August 2024)
Borrower acquired: Verona Pharma, by Merck (October 2025); Marinus Pharmaceuticals, by Immedica (February 2025); Paratek Pharmaceuticals, taken private by Gurnet Point and Novo Holdings with Oaktree debt (2023)
Restructured in Chapter 11: SiO2 Medical Products (2023, now Oaktree-owned); Athenex (2023); Impel Pharmaceuticals (2023 to 2024); BioXcel Therapeutics (filed August 2026)
Earlier loans: Sorrento Therapeutics (2018, repaid 2020); Innocoll Biotherapeutics (2022); the first Fortress Biotech loan (2020)
Investors
Who backs the fund is not public. No pension board paper, sovereign fund report or insurer filing reviewed for this profile names a commitment to either life sciences vehicle. The 2023 close was described as oversubscribed and drawn from institutions around the world. The investor counts in the Form D filings are the only numbers on record.
The partners on individual deals are easier to see. Qatar Investment Authority lent with Oaktree at BioXcel in 2022 and lends with it again in the bankruptcy. OMERS Life Sciences shared both Verona instruments. Sagard Healthcare Partners bought the Klisyri interest with Oaktree, having taken $50M of the Athenex loan by assignment in 2020.
Brookfield's insurance arm buys private credit in bulk. In the second quarter of 2026 Brookfield Asset Management raised $51B for private credit, $45B of it from Brookfield Wealth Solutions. Nothing published says that any of it has gone to life sciences lending.
Governance and Team
The Brookfield deal changed Oaktree's ownership and left its leaders in place. Howard Marks and Bruce Karsh remain co-chairs, and Karsh is chief investment officer. Robert O'Leary and Armen Panossian run Brookfield's Credit Group, which the same release sizes at $365B.
Panossian was also named co-portfolio manager of the life sciences fund at its close. Besides a law degree and an MBA from Harvard he holds a master's degree from Stanford Medical School. His co-manager, Aman Kumar, trained as a surgeon in Britain's National Health Service, traded European high-yield bonds at Deutsche Bank and joined Oaktree in 2014. Two managing directors work with them: Rahul Anand, who came from Morgan Stanley in 2020, and Kent Bailey, who joined in 2015. The 2025 filing counts 12 investment staff on the team.
Regulatory note: On 25 September 2024 the SEC settled with Oaktree Capital Management for a $375,000 penalty over late beneficial-ownership and insider filings. None of the issuers named in the order was a life sciences borrower. No SEC action or borrower lawsuit aimed at the life sciences business has been found.
Litigation note: In the SiO2 case the unsecured creditors' committee objected in April 2023 to the terms of Oaktree's bankruptcy loan, which it called too favourable to a lender that was also the proposed buyer. The plan was confirmed in July 2023 with objections resolved. Seres's proxy statement records that Oaktree alleged defaults, which Seres disputed, before the loan was repaid in full.
IP, Royalties and Return Economics
Impel Pharmaceuticals and the Trudhesa Interest
The first pairing was on a migraine spray. On 17 March 2022 Oaktree lent Impel $50M at 8.75 percentage points over SOFR. It paid a further $50M for a share of the sales of Trudhesa. Impel was the first borrower to owe Oaktree both a loan and a revenue interest, and the only one where Oaktree bought the interest alone.
The interest paid 7.75 percent of American net sales up to $150M a year, 4.75 percent on the next $150M and 0.75 percent above that. Payments stopped once Oaktree had received 175 percent of its money. If it had not been repaid in full by February 2027, the top rate rose to 10.75 percent.
The interest lasted less than two years. During 2023 Oaktree exchanged $9.0M and then $41.0M of it into first-lien term loans and advanced small sums of new money while it held off enforcing a covenant. Impel filed for Chapter 11 that December with $121.5M of secured loans. Two months later its assets were sold to JN Bidco LLC for $17.5M in cash plus contingent payments.
BioXcel Therapeutics and the Igalmi Interest
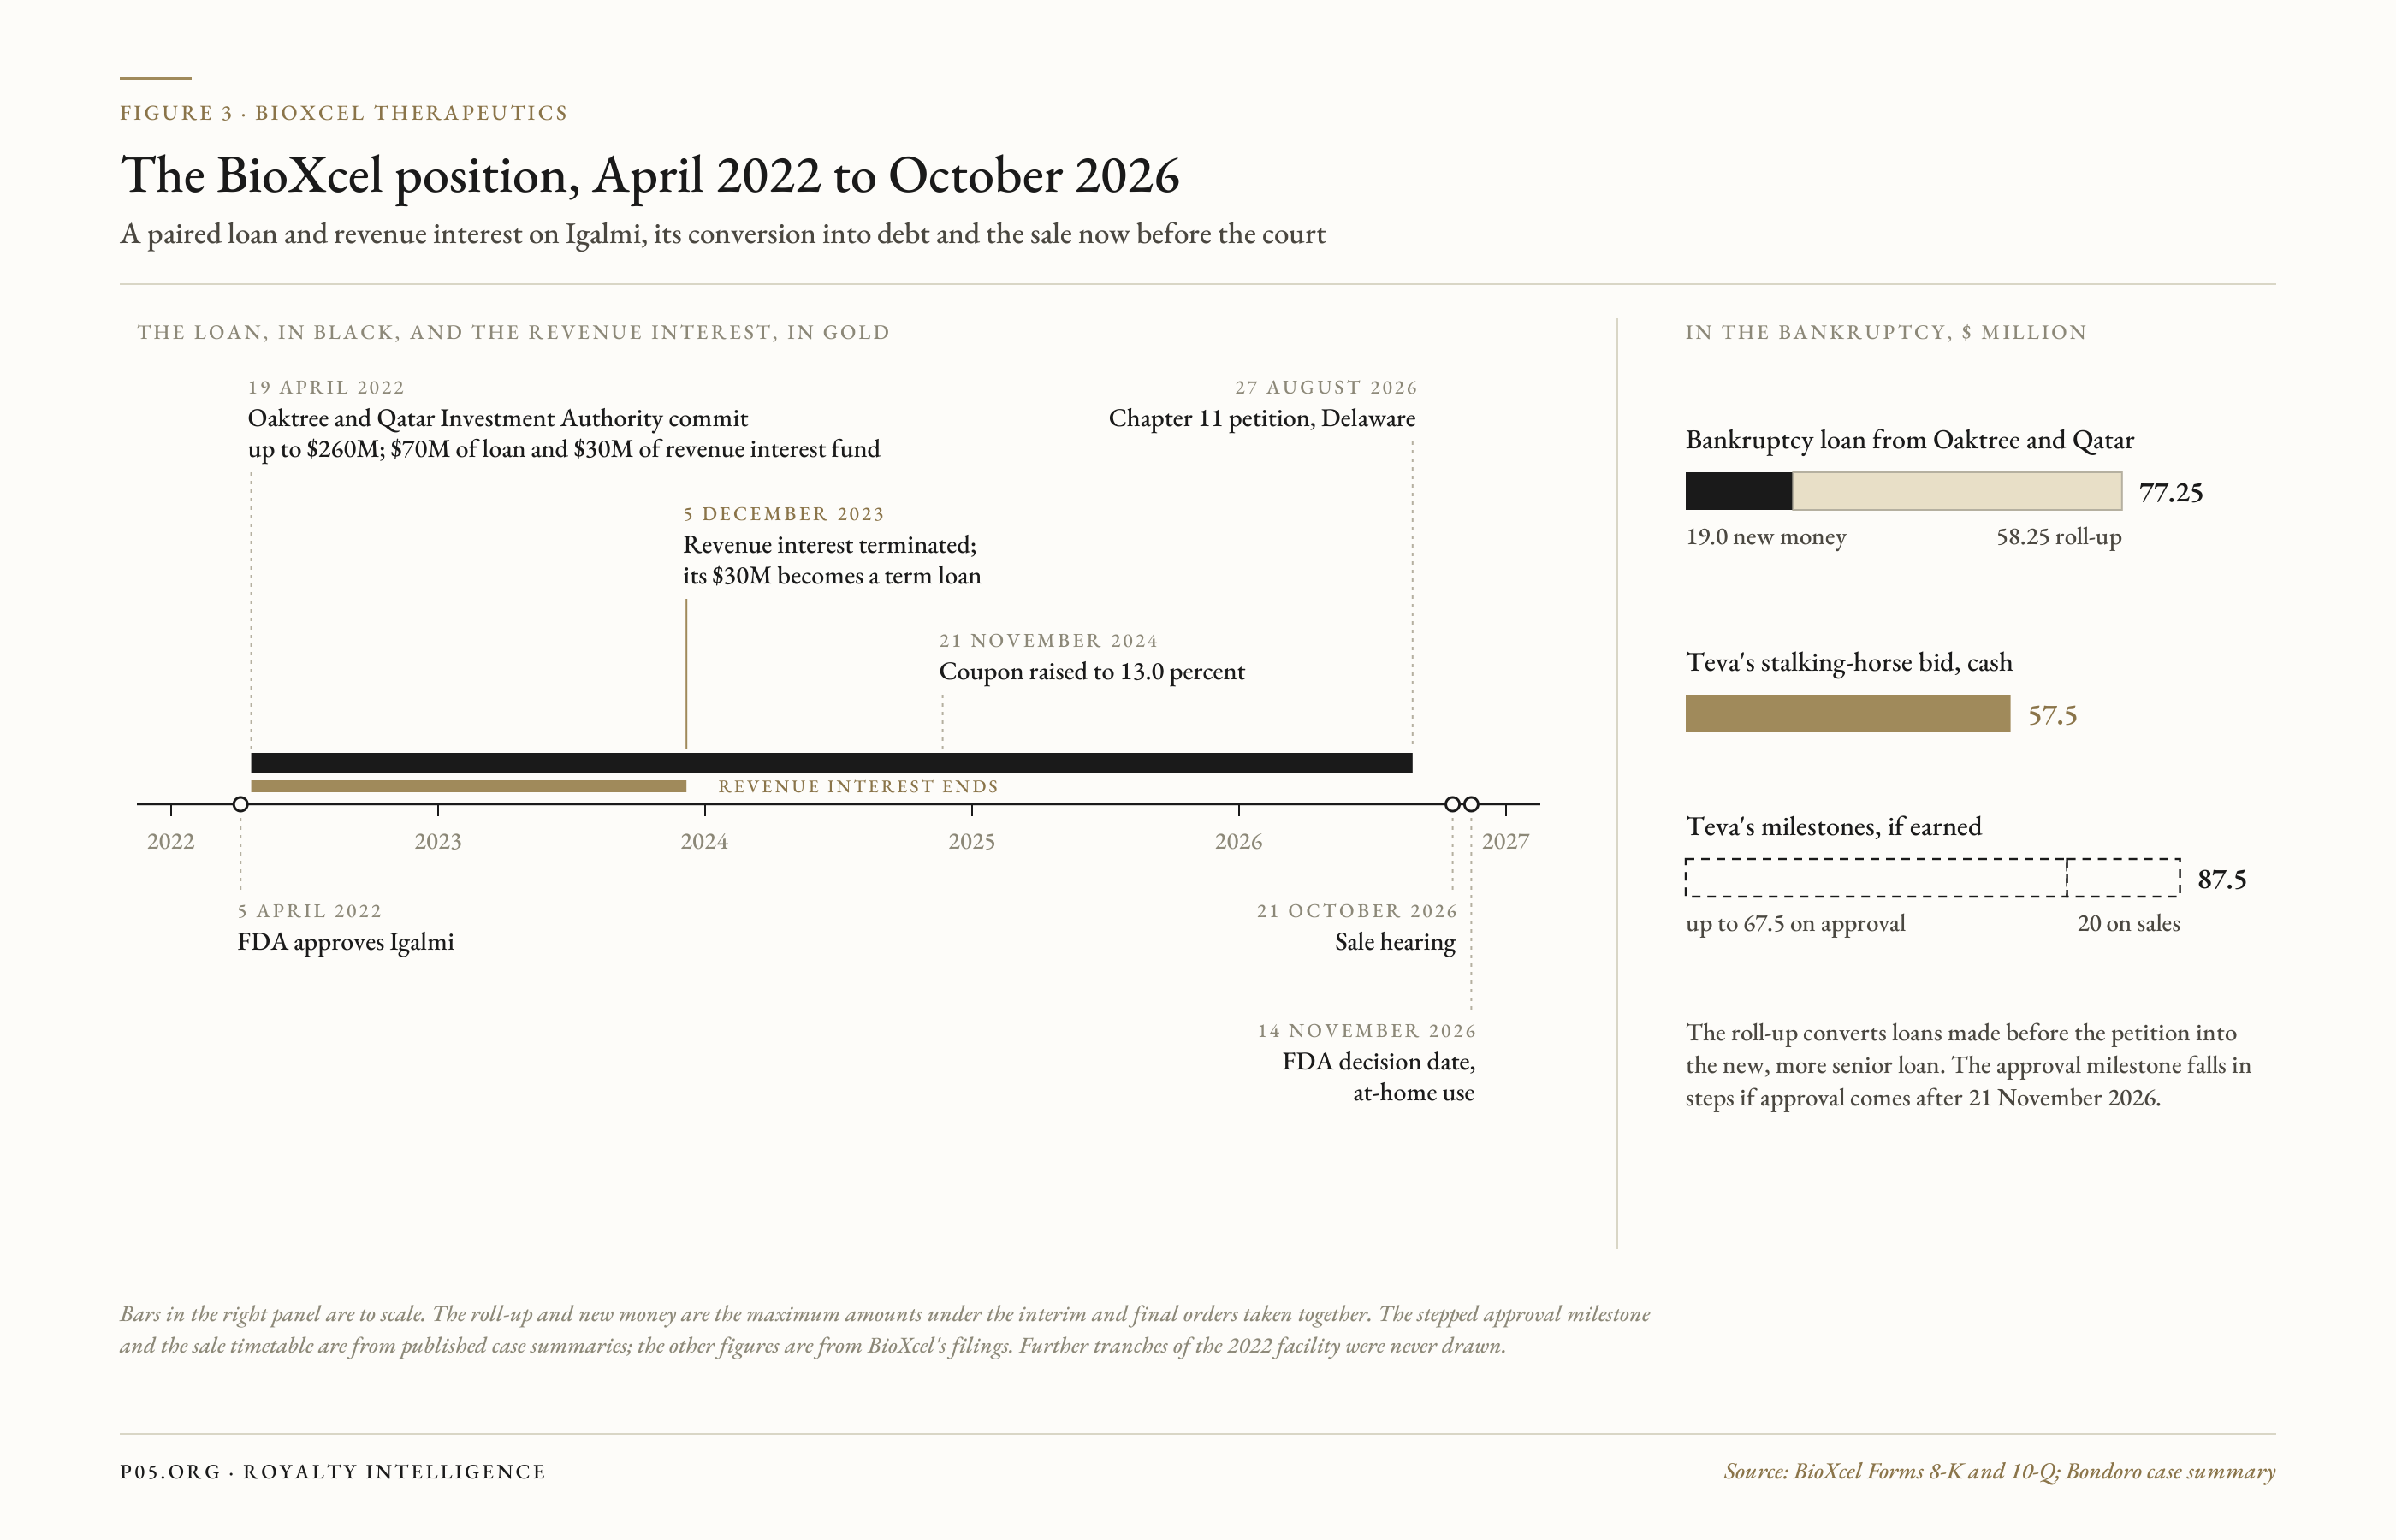
A month after Impel, Oaktree repeated the design at more than twice the size and with a partner. BioXcel's April 2022 financing joined a $135M term loan to a $120M revenue interest, both shared with Qatar Investment Authority. The filed agreement sets three rates on American net sales of Igalmi, at 7.75, 2.75 and 0.375 percent, and blacks out the sales levels at which each applies. The cap was again 1.75 times. BioXcel could buy the interest back for 1.225 times in the first year, rising to 1.75 after the third. The purchasers could demand the same price if the company went bankrupt or changed hands.
Only the first slice of each instrument was ever paid over: $70M of loan and $30M of revenue interest. Twenty months later, on 5 December 2023, the revenue interest agreement was terminated. Its $30M became Tranche A-2 of the term loan. The lenders' warrants, struck at $20.04 a share in 2022, were repriced to $3.65.
The loan's coupon, 10.25 percent at signing, had risen to a fixed 13.0 percent by mid-2026. BioXcel filed for Chapter 11 on 27 August 2026, three days after the last amendment to its credit agreement.
Oaktree and Qatar Investment Authority are lending up to $77.25M to see the case through. Of that, $19M is new money. The other $58.25M is a roll-up, which converts debt owed before the filing into the new loan and so ranks it ahead of other claims. Teva is the stalking-horse bidder, meaning that its offer sets the floor for an auction. It has bid $57.5M in cash plus milestones that depend on approval of Igalmi for use at home and on later sales.
Athenex and the Klisyri Royalties
The third interest, in June 2022, was a different sort of deal. Athenex had borrowed up to $225M from Oaktree in 2020 at a fixed 11.0 percent. It also owned a royalty owed by a third party: Almirall paid it on sales of Klisyri in America and Europe.
Athenex and a new subsidiary, ATNX SPV, LLC, sold those royalties and the related milestones to Sagard and Oaktree funds for $85.0M. Half the price, $42.5M, went straight back to Oaktree to pay down its loan. Oaktree and Sagard each took 10 percent of the subsidiary's shares and a seat on its board. No other purchase by Oaktree of a third party's royalty has been found.
Athenex filed for Chapter 11 eleven months later, owing Oaktree about $41.9M. A vehicle with the subsidiary's name is still on Oaktree's books. Oaktree Specialty Lending's schedule for 30 June 2026 lists a first-lien loan to ATNX SPV, LLC due in May 2031, footnoted as a revenue interest financing whose payments depend on a percentage of revenues. It is valued at 97 percent of principal.
Verona Pharma and the Ensifentrine Interest
Two years passed before Oaktree used the paired design again. The Verona package of 9 May 2024, shared with OMERS, offered term loans of up to $400M in five tranches. With them came a Revenue Interest Purchase and Sale Agreement of up to $250M. It would fund $100M when regulators approved ensifentrine and $150M on a sales milestone. The purchasers were to receive 6.50 percent of global net sales until they had collected 1.75 times their money. Verona could buy them out for 1.20 times in the first year, 1.40 in the second and 1.55 in the third.
Approval came in June 2024 and the first $100M was paid. The second tranche never was. On 25 March 2025 Verona exercised its right to buy the interest back, and the purchasers agreed to lower the first-year price from 1.20 to 1.17 times. Verona's next quarterly report puts the repurchase amount at $109.9M.
Two days later the lenders enlarged the loan. Tranche C grew from $75M to $125M and was drawn, which took the balance to $250M. The coupon fell from 11.00 to 9.70 percent. Verona had swapped a 6.50 percent claim on the revenue of Ohtuvayre, as ensifentrine is sold, for more senior debt from the same two lenders at a lower rate than before. Merck completed its purchase of the company on 7 October 2025. The closing 8-K does not say how the Oaktree loan was settled.
Absent Royalties
After Verona the revenue leg disappears. Establishment Labs, Aquestive, ADC Therapeutics, OXB, Harrow, Seres, Mesoblast, Fortress and Paratek carry no Oaktree royalty in the filings. Some of them owe a revenue interest to another investor, and there Oaktree appears as the senior creditor. At Aquestive its lien is subject to an RTW purchase agreement and an intercreditor agreement. At Marinus, Sagard's 2022 royalty needed Oaktree's consent and an intercreditor with Oaktree as agent.
Blue Team
- A 13-year record in one sector: $6.2B across 54 investments, reported with no realised losses through 31 December 2025
- Capacity to lend large sums alone or with one partner, up to $650M at Verona, which lets a borrower settle loan and revenue interest with a single counterparty and one set of documents
- Repeat borrowers: Establishment Labs refinanced its 2022 facility with a larger Oaktree loan in April 2026, and OXB did the same in August 2025
- Exits at contractual economics where the product worked: Verona's interest returned 1.17 times in nine months, and Seres paid a $12.5M yield protection premium on early repayment
- A demonstrated ability to control a workout from the senior position, by converting junior claims, funding the bankruptcy and bidding its debt, as at SiO2 and Athenex and now BioXcel
- New lending in 2026, with $265M funded to Establishment Labs in April and $55M to Aquestive in May
- An owner with a $365B credit platform and an insurance balance sheet that buys private credit in large amounts
Red Team
- Four borrowers have filed for Chapter 11 since 2023: SiO2, Athenex, Impel and BioXcel. All four loans were written between 2020 and 2022. The stated record of no realised losses runs to December 2025 and the filing does not define the term; a position such as SiO2, which Oaktree owns after a debt-for-equity plan, has not been realised
- The public marks are low on the restructured names. Oaktree Specialty Lending carries its SiO2 and JN Bidco common stock at zero against a combined cost of about $58M. These are one vehicle's slices and say nothing direct about the private fund's result
- Three of four revenue interests did not run their course as royalties. Two were exchanged into loans when the product undersold. The third was called early when the product succeeded, which capped the return at 1.17 times on a contract that allowed 1.75
- Teva's stalking-horse bid for BioXcel's assets is $57.5M in cash against a bankruptcy loan of up to $77.25M. Recovery above the cash price depends on milestones and on any higher bid at auction
- Oaktree has more than once held the loan, the junior claim and the bankruptcy financing in the same case. The SiO2 creditors' committee raised that point in court, and it was settled before confirmation
- No fund investor is named and no return is published. Nothing public has appeared on the Income Fund since its January 2025 Form D
- Payoff terms on the Verona and Marinus loans at acquisition are not disclosed in the filings reviewed, so the realised return on the largest facility in the book cannot be computed from the public record
- How the strategy will be staffed and funded inside Brookfield's Credit Group has not been addressed in any Brookfield or Oaktree statement since completion
Implications for the Pharmaceutical Royalty and Biotech Capital Markets
Set side by side, the three interests that Oaktree wrote share the features of a secured loan. In each the purchaser, the agent and the senior lender were one firm. The interest was secured. A schedule of multiples fixed the price of exit for either side. An investor whose return must fall between 1.2 and 1.75 times, and who can hand the interest back if the company is sold, holds something close to a second-lien loan with a coupon that moves with sales.
That design made the interest easy to abandon. In 2023, when Impel and BioXcel needed relief, the lenders folded it into the first-lien loan by amendment. There was no outside royalty holder to persuade and no intercreditor dispute to settle, because the same funds sat on both sides.
The convenience has a cost for anyone who studies how revenue interests fare in bankruptcy. Neither case tested one. By the day each company filed, the claim was a term loan. Whether the original interest was a true sale or a disguised loan, and who owned the revenue earned after the petition, are questions that never reached a judge.
Verona shows what the same structure does when the drug sells. The contract promised as much as 1.75 times. It paid 1.17, because the company bought the interest back inside the first year and the purchasers took a lower price in the week that their loan was enlarged. When a launch goes well and the borrower can refinance, the first-year price sets the return.
Royalty funds mostly meet Oaktree as the senior lender across an intercreditor agreement, as Sagard did at Marinus and RTW does at Aquestive. The Klisyri purchase is the one occasion on which Oaktree bought a third-party stream beside a royalty fund, and half the price repaid its own loan. Nothing in the record for 2025 or 2026 shows it bidding for a royalty in a contest.
Since Verona the firm has lent without a revenue leg, at Establishment Labs, OXB and Aquestive. Oaktree has not said whether it has given up the paired design or has lent to companies that did not need it, and the mandate of the Income Fund is unpublished.
Recent Developments
- Fortress Biotech repays its Oaktree loan in full, $15.0M of principal with a $150,000 prepayment fee, on 30 September 2026
- The BioXcel sale process sets a bid deadline of 9 October, an auction on 14 October and a sale hearing on 21 October 2026, according to a published case summary
- BioXcel Therapeutics files for Chapter 11 with Oaktree and Qatar Investment Authority as bankruptcy lenders and Teva as stalking-horse bidder on 27 August 2026
- Brookfield announces completion of its acquisition of Oaktree on 3 August 2026
- Aquestive Therapeutics closes a $150M facility with Oaktree as sole lender on 12 May 2026
- Establishment Labs closes a $300M facility that repays its 2022 Oaktree loan on 30 April 2026
- Mesoblast repays its Oaktree loan from a new facility on 30 December 2025
- Merck completes its acquisition of Verona Pharma on 7 October 2025
- Harrow prices $250.0M of senior notes to prepay its Oaktree loan in September 2025
- OXB signs a new facility of up to $125M on 1 August 2025
- No new Oaktree revenue interest, purchased royalty or synthetic royalty has been identified in 2025 or 2026
Financial History and Recent Developments
| Date | Event |
|---|---|
| 1995 | Oaktree Capital Management founded |
| 2013 | Oaktree begins investing in life sciences |
| 7 Nov 2018 | Sorrento Therapeutics term loan, $100M funded; repaid 12 June 2020 |
| 30 Sep 2019 | Brookfield completes acquisition of about 61.2 percent of Oaktree |
| 19 Jun 2020 | Athenex credit agreement, up to $225M at 11.0 percent |
| Apr 2021 | Panossian and Kumar publish their paper on life sciences direct lending |
| 17 May 2021 | Marinus Pharmaceuticals facility, up to $125M |
| 19 Nov 2021 | Mesoblast facility, $90M; $60M drawn |
| 22 Dec 2021 | SiO2 Materials Science facility, $205M |
| 17 Mar 2022 | Impel: $50M loan and $50M Trudhesa revenue interest |
| 19 Apr 2022 | BioXcel: up to $260M with Qatar Investment Authority; $70M loan and $30M revenue interest funded |
| 26 Apr 2022 | Establishment Labs facility, $225M |
| 21 Jun 2022 | Sagard and Oaktree buy Klisyri royalties and milestones for $85.0M |
| 15 Aug 2022 | ADC Therapeutics term loan, up to $175M, with Owl Rock |
| 29 Mar 2023 | SiO2 files for Chapter 11; plan confirmed July 2023 |
| 27 Apr 2023 | Seres Therapeutics facility, $250M; $110M drawn |
| 14 May 2023 | Athenex files for Chapter 11 |
| 26 Jun 2023 | Oaktree Life Sciences Lending Fund closes above $2.3B |
| 5 Dec 2023 | BioXcel revenue interest terminated; $30M converted to term loan |
| Dec 2023 | Impel files for Chapter 11; assets sold for $17.5M in February 2024 |
| 9 May 2024 | Verona: up to $400M of loans and a $250M revenue interest, with OMERS |
| 30 Sep 2024 | Seres repays about $128.0M on the sale of Vowst |
| 29 Jan 2025 | Oaktree Life Sciences Income Fund files Form D |
| 25 Mar 2025 | Verona calls its revenue interest at 1.17 times |
| 1 Aug 2025 | OXB facility, up to $125M |
| 7 Oct 2025 | Merck completes acquisition of Verona |
| 13 Oct 2025 | Brookfield agrees to buy the rest of Oaktree for about $3B |
| 30 Dec 2025 | Mesoblast repays Oaktree |
| 30 Apr 2026 | Establishment Labs facility, $300M |
| 12 May 2026 | Aquestive facility, $150M |
| 3 Aug 2026 | Brookfield announces completion |
| 27 Aug 2026 | BioXcel files for Chapter 11 |
| 30 Sep 2026 | Fortress Biotech repays Oaktree |
Conclusion
Oaktree's life sciences business has lent about $6.2B over 13 years and now belongs wholly to Brookfield. It has a dedicated fund of $2.3B and a second vehicle that is registered and otherwise undescribed. Its loans are released in stages as a drug wins approval and sells, and they charge the borrower for leaving early. At Verona and Seres the product sold and Oaktree collected those charges. Four other borrowers ended in Chapter 11, most of them with Oaktree lending into the bankruptcy.
Royalties were a brief addition to that business. Between March 2022 and May 2024 the firm wrote three revenue interests beside its own loans and bought one third-party stream with Sagard. Verona bought its interest back. The other two were absorbed into debt, and only the Klisyri position can still be seen.
The Delaware hearing on 21 October will settle the last of the three. Whatever Teva or a rival bidder pays for Igalmi will go first to the lenders, whose claim includes the $30M once advanced as a revenue interest.
All information in this report was accurate as of the research date and is derived from publicly available sources including court opinions, regulatory guidance, academic literature, SEC filings, and financial news reporting. Information may have changed since publication. This content is for informational purposes only and does not constitute investment, legal, or financial advice. The author is not a lawyer or financial adviser.