Fund of the Week: Petrichor Healthcare Capital Management
Petrichor's seed investor described it in 2017 as a firm that would buy royalties as well as lend and take equity. Nine years and at least fifteen companies later, its public record holds notes and shares. Most of the notes became shares. The one that did not was repaid by a company whose European royalty sat inside Petrichor's collateral.
On 21 September 2026 Telix Pharmaceuticals agreed to buy ITM Isotope Technologies Munich, a German maker of radiopharmaceuticals, for $1.65B on a cash-free and debt-free basis.
About $1.25B of the price is paid in Telix shares. Up to $700M more depends on approvals and sales of ITM-11, a treatment for neuroendocrine tumours. Telix also takes on $302M of net debt.
In April 2021 Petrichor Healthcare Capital Management led a convertible loan of $109M (EUR 90M) to ITM, and Tadd Wessel, its founder, joined the supervisory board. The loan turned into shares under its own terms when ITM raised its next round in June 2023.
ITM's debt is now owed to another lender. In June it said that its financing of up to $262.5M had moved from Blue Owl funds to Perceptive, which was profiled in the previous issue.
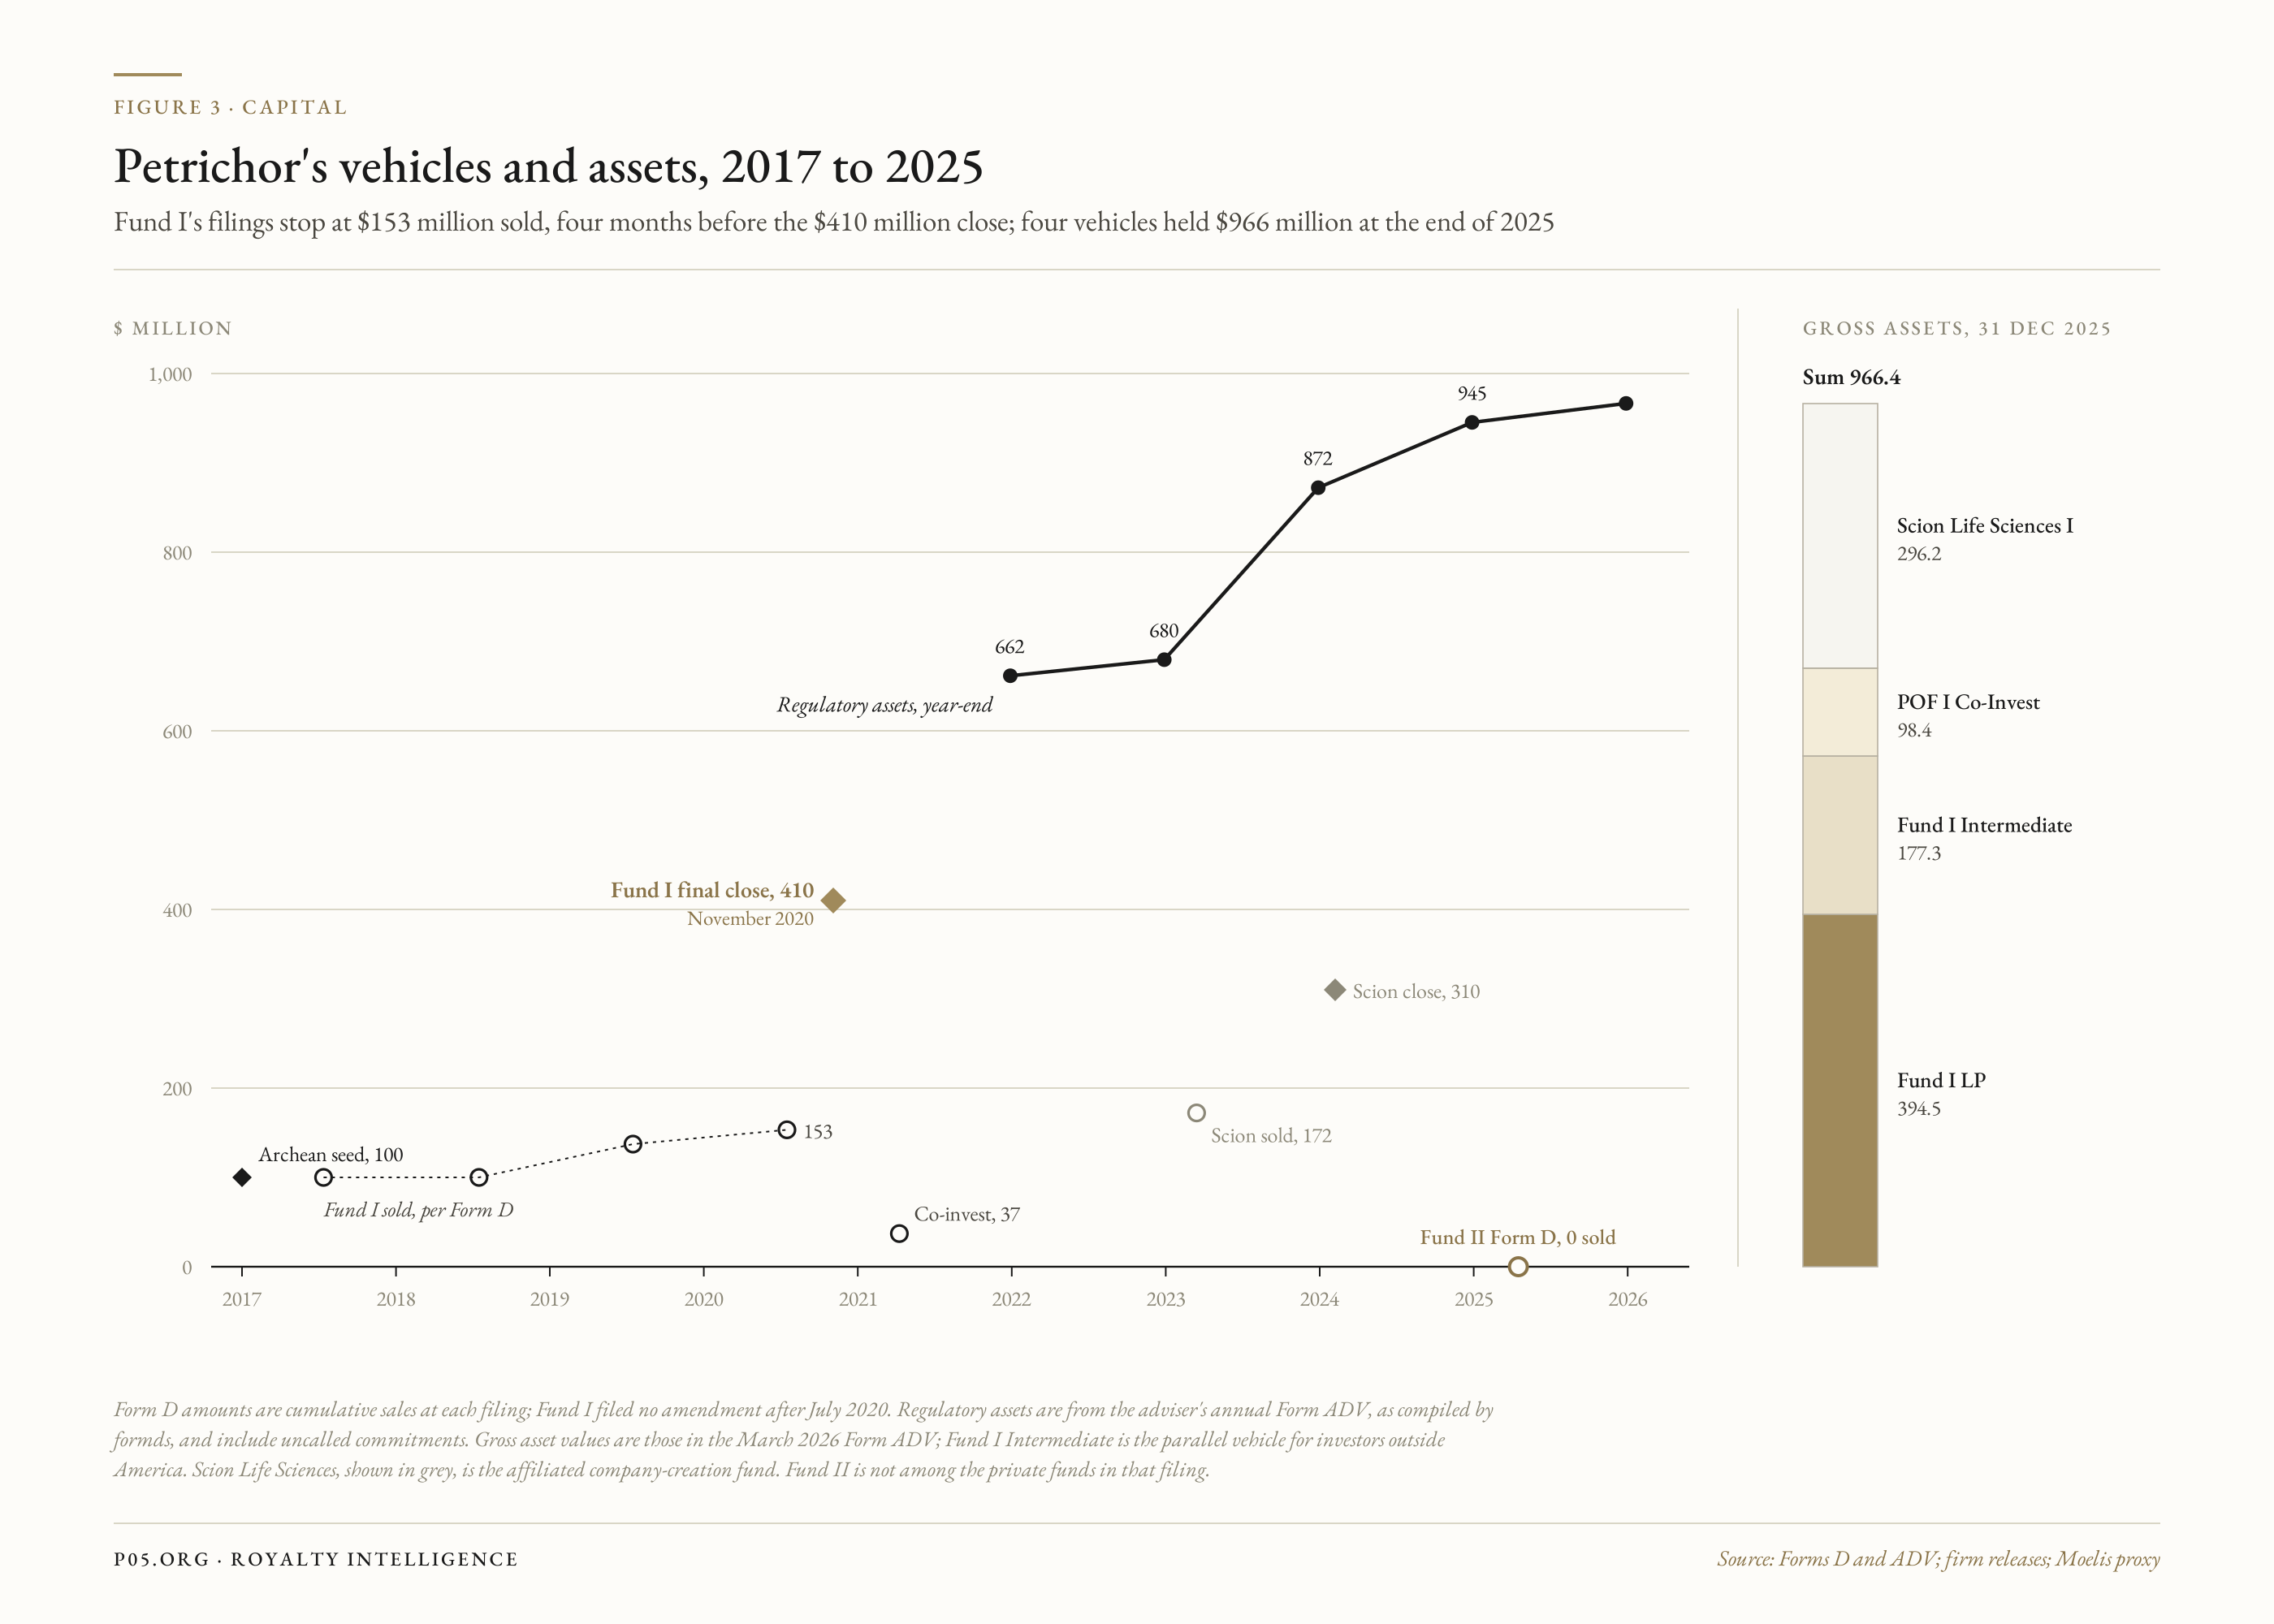
A Petrichor note usually ends that way. Of seven convertible instruments in the public record, four became shares. Two ended in ways that have not been disclosed. The seventh, at Fennec Pharmaceuticals, was redeemed in November 2025 for $21.7M, at 110 percent of principal.
Moelis & Company, whose joint venture supplied Petrichor's seed money, described the new firm to its shareholders in 2017 as one that makes "structured credit, royalty, and equity investments in the healthcare sector".
The record since then shows a firm whose debt is mostly a way into a company's equity. It holds no royalty. Its closest contact with one came at Fennec, where a licence that pays Fennec royalties in Europe was written around Petrichor's security.
At a Glance
- What it is: a New York investor in late-stage and commercial healthcare companies, public and private, that writes convertible notes, secured loans, and preferred equity, with an affiliated company-creation fund, Scion Life Sciences
- Manager: Petrichor Healthcare Capital Management LP, formed in January 2017 by Tadd Wessel and based at 220 East 42nd Street, New York; its website now presents the business as Petrichor Capital Partners
- Seed capital: $100M from Archean Capital Partners I, a joint venture of Moelis Asset Management and Veritable, committed in January 2017
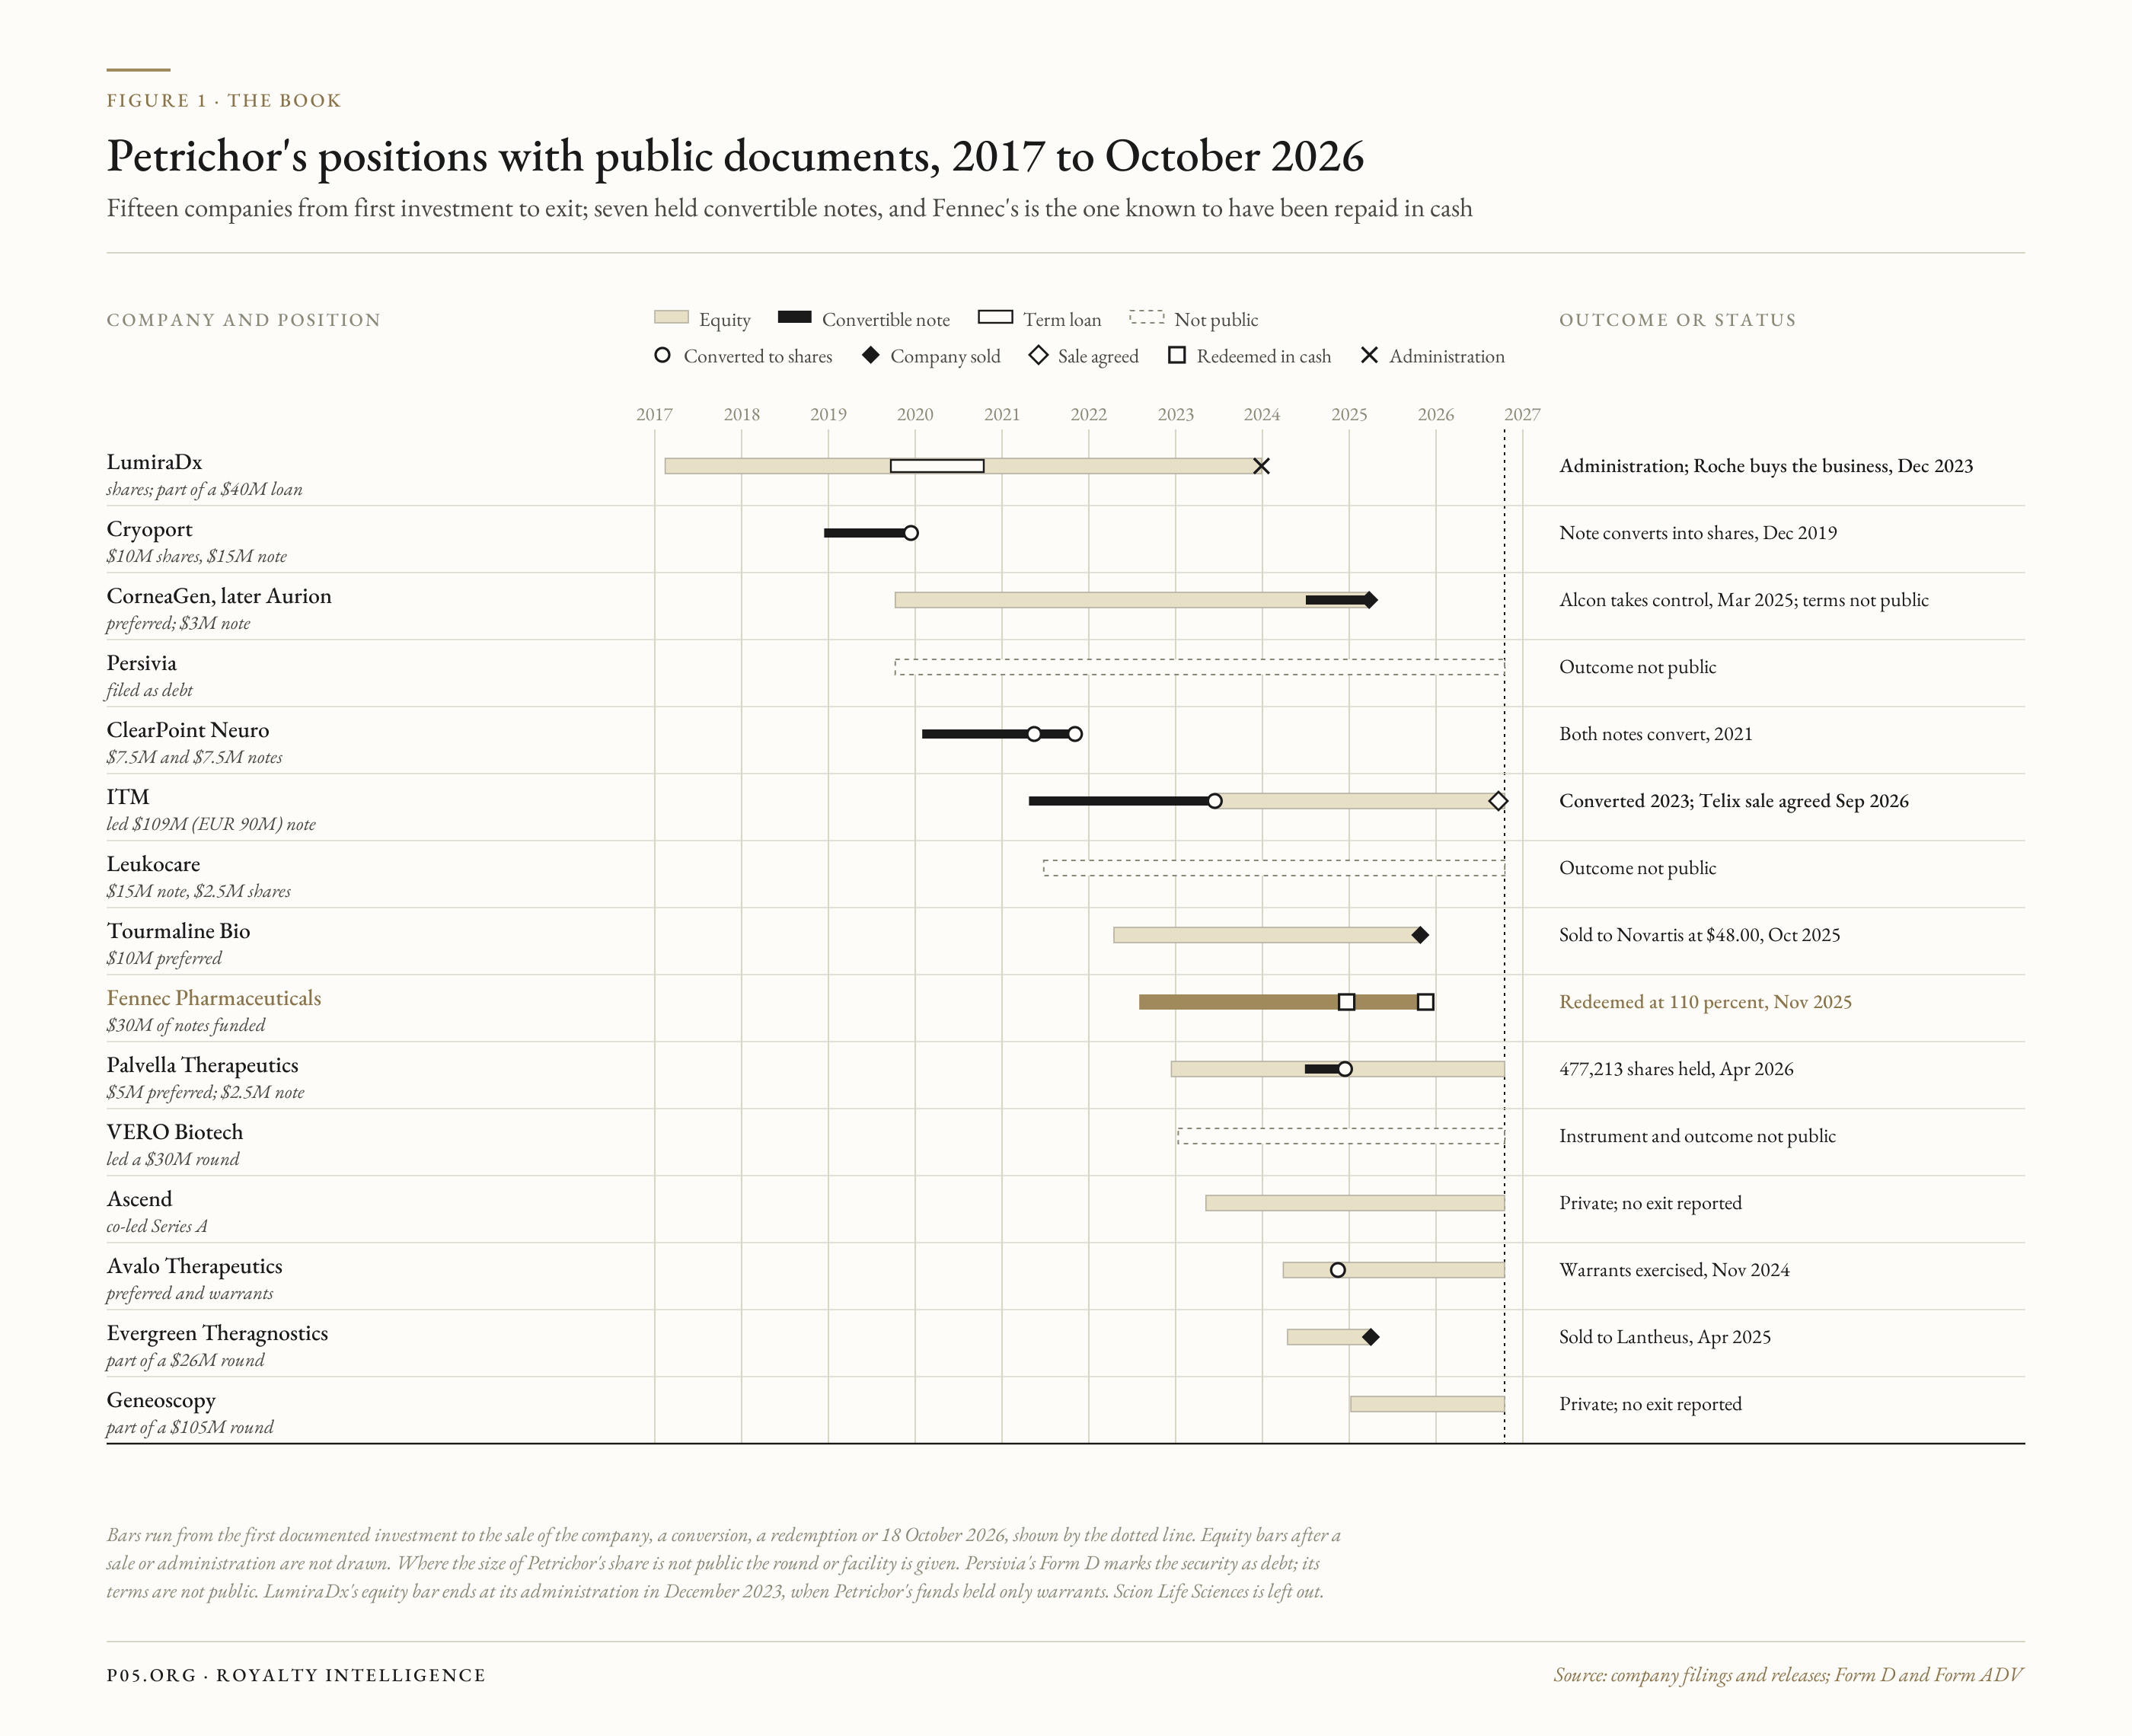
- Regulatory assets under management: $966.5M at 31 December 2025, across six accounts
- Funds: Petrichor Opportunities Fund I, $410M at its final close in November 2020; POF I Co-Invest, $37M in 2021; Scion Life Sciences I, $310M in February 2024; Petrichor Capital Partners Fund II, notified to the SEC on 17 April 2025 with no sales at filing
- Placement agent: Moelis & Company, the only one named on any Fund I filing
- Partners: Tadd Wessel, managing partner, with Patrick Lally and Michael Beecham, both partners since the launch
- Staff: 16 employees, 12 of them in investment roles, at the March 2026 filing
- Companies with public documents: 15, from LumiraDx in February 2017 to Geneoscopy in January 2025
- Royalty interests written or bought: none found
A Note on Scope
Petrichor runs two strategies under one adviser. This profile covers the structured growth business, which invests through Fund I and its parallel and co-investment vehicles. Scion Life Sciences, which forms biotech companies, is left out except where a Scion partner sits on the board of a company that Fund I holds.
The firm's website credits its team with more than 100 investments and more than $3B invested, and its 2026 releases give more than 125 investments and more than $6B. Both totals include the partners' earlier careers at OrbiMed and Fortress. The fifteen companies in this profile are those for which a filing, a release or a court document names a Petrichor fund.
Fund I publishes no portfolio and no returns. Deal terms come from borrowers' filings. For the private companies, among them Leukocare, VERO Biotech, Ascend, and Geneoscopy, the size of the round is public and Petrichor's share of it is not.
Investment Thesis and Mandate
Mr Wessel was a partner at OrbiMed, where he led the build-out of its structured investment business, and before that a vice-president at Fortress. He left to found Petrichor in January 2017.
Archean, the Moelis and Veritable joint venture, made Petrichor its first investment. In return for $100M of seed money, Archean I takes a revenue share of all Petrichor revenue, capped by a test on its return. Moelis Asset Management receives 12.5 percent of that share, and Moelis & Company agreed to act as placement agent.
The proxy that disclosed the arrangement described the mandate as credit, royalty, and equity. When Fund I closed in November 2020, the firm described structured investments in private and public companies seeking growth capital, of $10M to $50M each, with more available from its investors as co-investment. Royalties were not mentioned.
The firm's Form ADV brochure for 2026 lists first-lien loans, subordinated loans, common and preferred stock, warrants, and convertible securities. It aims for equity returns with the protection of credit and some cash yield. The list has no royalty.
The portfolio follows the brochure. Petrichor has lent to companies with a product on sale or close to approval, such as Cryoport, ClearPoint Neuro, and Fennec, and it has bought preferred stock in private companies a round or two before a listing or a sale, such as Tourmaline, Palvella, and Evergreen Theragnostics.
Several companies received both. At Cryoport in December 2018 Petrichor bought $10M of shares and a $15M convertible note on the same day.
Since 2023 the weight has moved toward equity. VERO Biotech, Ascend, Evergreen, and Geneoscopy were all equity rounds or rounds with undisclosed instruments, and the Avalo investment of March 2024 was preferred stock with warrants.
The Fennec notes of 2022 are the last new debt instrument in the public record, apart from two small convertible notes in 2024 at Aurion and Palvella that were bought beside other insiders ahead of a planned listing.
How Capital Enters and Returns
Fund I is a Delaware partnership with a parallel vehicle for investors outside America. The Form D filings stop in July 2020, when $153.35M had been sold to 14 investors, four months before the $410M close.
The adviser's Form ADV for 2025 values the main partnership at about $394.5M gross with 54 beneficial owners and a minimum commitment of $5M. Petrichor Opportunities Fund I Intermediate LP, the parallel vehicle, holds about $177.3M for two owners, all of them outside America. Both vehicles appear as holders on several later deals.
The fee terms are in the brochure. The firm charges up to 2 percent a year on commitments during the investment period and offsets 80 percent of transaction fees against it. Organisational expenses are capped at $1.25M.
The usual instrument is a convertible note. It pays a floating rate with a floor, often partly in kind, meaning that the interest is added to the principal. It converts at a premium to the share price at signing, and the company pays a premium to repay it early.
At Fennec the coupon was the prime rate, floored at 3.5 percent, plus 4.5 percent, with 3.5 percent paid in kind for two years and conversion 20 percent above the market. At ClearPoint the first note paid three-month LIBOR, floored at 2 percent, plus 2 percent, and converted at $6.00.
Petrichor has also lent in a syndicate. It was one of five lenders when Kennedy Lewis led a $40.0M loan to LumiraDx in September 2019 at a fixed 11.5 percent, with warrants. LumiraDx prepaid it in October 2020. Preferred stock, bought in priced rounds beside venture funds, makes up the rest of the book.
A note returns capital as shares or as cash. If the share price passes the conversion price, the fund takes shares. Cryoport's note converted into 1,172,305 shares a year after signing, and both ClearPoint notes converted in 2021.
If it does not, the company repays in cash with the premium, as Fennec did. The equity then leaves through a sale of the company. Novartis completed its purchase of Tourmaline at $48.00 a share in October 2025, and Lantheus completed its purchase of Evergreen in April 2025.
Financial Profile and Assets
| Item | Amount | Source and Date |
|---|---|---|
| Regulatory assets under management | $966.5M | Form ADV, via formds, 31 Dec 2025 |
| Seed commitment from Archean Capital Partners I | $100M | Moelis proxy, Jan 2017 |
| Petrichor Opportunities Fund I, final close | $410M | Firm release, Nov 2020 |
| Fund I and Fund I Intermediate, gross assets | about $394.5M and $177.3M | Form ADV, 31 Dec 2025 |
| POF I Co-Invest LP | $37.0M sold; $98.4M gross assets at end-2025 | Form D, Apr 2021 |
| Scion Life Sciences I | $310M | Firm release, Feb 2024 |
| Petrichor Capital Partners Fund II | $0 sold at filing | Form D, 17 Apr 2025 |
| ITM convertible loan, led by Petrichor | $109M (EUR 90M) | ITM release, 22 Apr 2021 |
| Fennec convertible notes | up to $45M; $30M funded | 8-K, 4 Dec 2023 |
| Fennec partial redemption | $13.0M of principal and capitalised interest | 8-K, 18 Dec 2024 |
| Fennec final redemption | $21.7M, including a $1.9M redemption fee | 8-K, 17 Nov 2025 |
| Cryoport shares and convertible note | $10M and $15M | 8-K, 17 Dec 2018 |
| ClearPoint convertible notes held by Petrichor | $7.5M and $7.5M | 8-K, 29 Dec 2020 |
| Leukocare convertible loan and equity | $15M and $2.5M | Private Equity Wire, 23 Jun 2021 |
| Palvella shares held by Petrichor funds | 477,213 | Proxy, 13 Apr 2026 |
Portfolio Book
Convertible notes, with outcome: Cryoport (converted, December 2019); ClearPoint Neuro (both notes converted, 2021); ITM Isotope Technologies Munich (converted, June 2023); Palvella Therapeutics (converted into a placement, December 2024); Fennec Pharmaceuticals (redeemed at 110 percent, November 2025); Leukocare (outcome not public); Aurion Biotech (outcome not public)
Term loans: LumiraDx, with Kennedy Lewis as lead lender (prepaid, October 2020); Persivia (filed as debt, terms and outcome not public)
Equity held at listed companies: Palvella Therapeutics (Nasdaq: PVLA); Avalo Therapeutics (Nasdaq: AVTX)
Private companies, instrument not disclosed or equity: VERO Biotech; Ascend Advanced Therapies; Geneoscopy; Leukocare; Persivia
Company sold: Tourmaline Bio, to Novartis (October 2025); Evergreen Theragnostics, to Lantheus (April 2025); Aurion Biotech, majority bought by Alcon (March 2025); ITM, agreed sale to Telix (September 2026, pending)
Company in administration: LumiraDx, whose point-of-care business Roche agreed to buy in December 2023, by which time Petrichor held only warrants
Investors
Archean is the only investor named in public. Beyond it, the record gives counts and types. Crain's New York reported at the close that Fund I had more than 25 investors, among them pension funds, foundations, and financial institutions in North America and Europe, with commitments of $5M to $100M and several at the top of that range.
No pension board paper or endowment report reviewed for this profile names a commitment.
As a seeding vehicle Archean holds a share of the manager's revenue as well as its interest in the fund. Archean's second fund, which closed above $425M in 2021, lists Petrichor among the investments of the first.
Co-investors appear deal by deal. PTC Therapeutics lent $10.0M beside Petrichor's $7.5M at ClearPoint, where PTC was also a commercial partner. Ligand Pharmaceuticals bought $2.5M of Palvella's convertible notes at the same closing as Petrichor in June 2024. Abingworth co-led the Ascend round, and Bio-Rad led Geneoscopy's.
Governance and Team
Mr Wessel owns 75 percent or more of the adviser. The two partners have worked with him since OrbiMed. Patrick Lally came from OrbiMed's special situations group after posts at Fortress's Drawbridge fund and Barclays. Michael Beecham worked at OrbiMed, Vatera, and American Capital, and earlier at Royalty Pharma.
A senior associate and two associates complete the investment team, with David Katona, formerly of Jefferies, in charge of business development and investor relations.
The firm added two operating partners in 2026: Paul Sekhri, a former chief executive of several biotech companies, in April, and Don Hardison, chairman of Geneoscopy, in May. Jeffrey Edelman became chief compliance officer and a partner in March 2026. An advisory board formed in 2018 includes Sir Bruce Keogh, the former medical director of NHS England, Peter Greenleaf, and Raymond Schinazi.
The partners take board seats on the larger positions. Mr Wessel has been a director of Palvella since December 2024 and joined ITM's supervisory board in 2021. Mr Lally joined the boards of Aurion and VERO, and Mr Beecham those of Fennec and Ascend. Aaron Kantoff of Scion joined Avalo's board in March 2024 and sat on Tourmaline's.
Regulatory note: The adviser has been registered with the SEC since January 2018. Its brochure records no disciplinary action against the firm or its managers, and no SEC order or litigation release naming it has been found.
IP, Royalties and Return Economics
Fennec Pharmaceuticals and the Norgine Licence
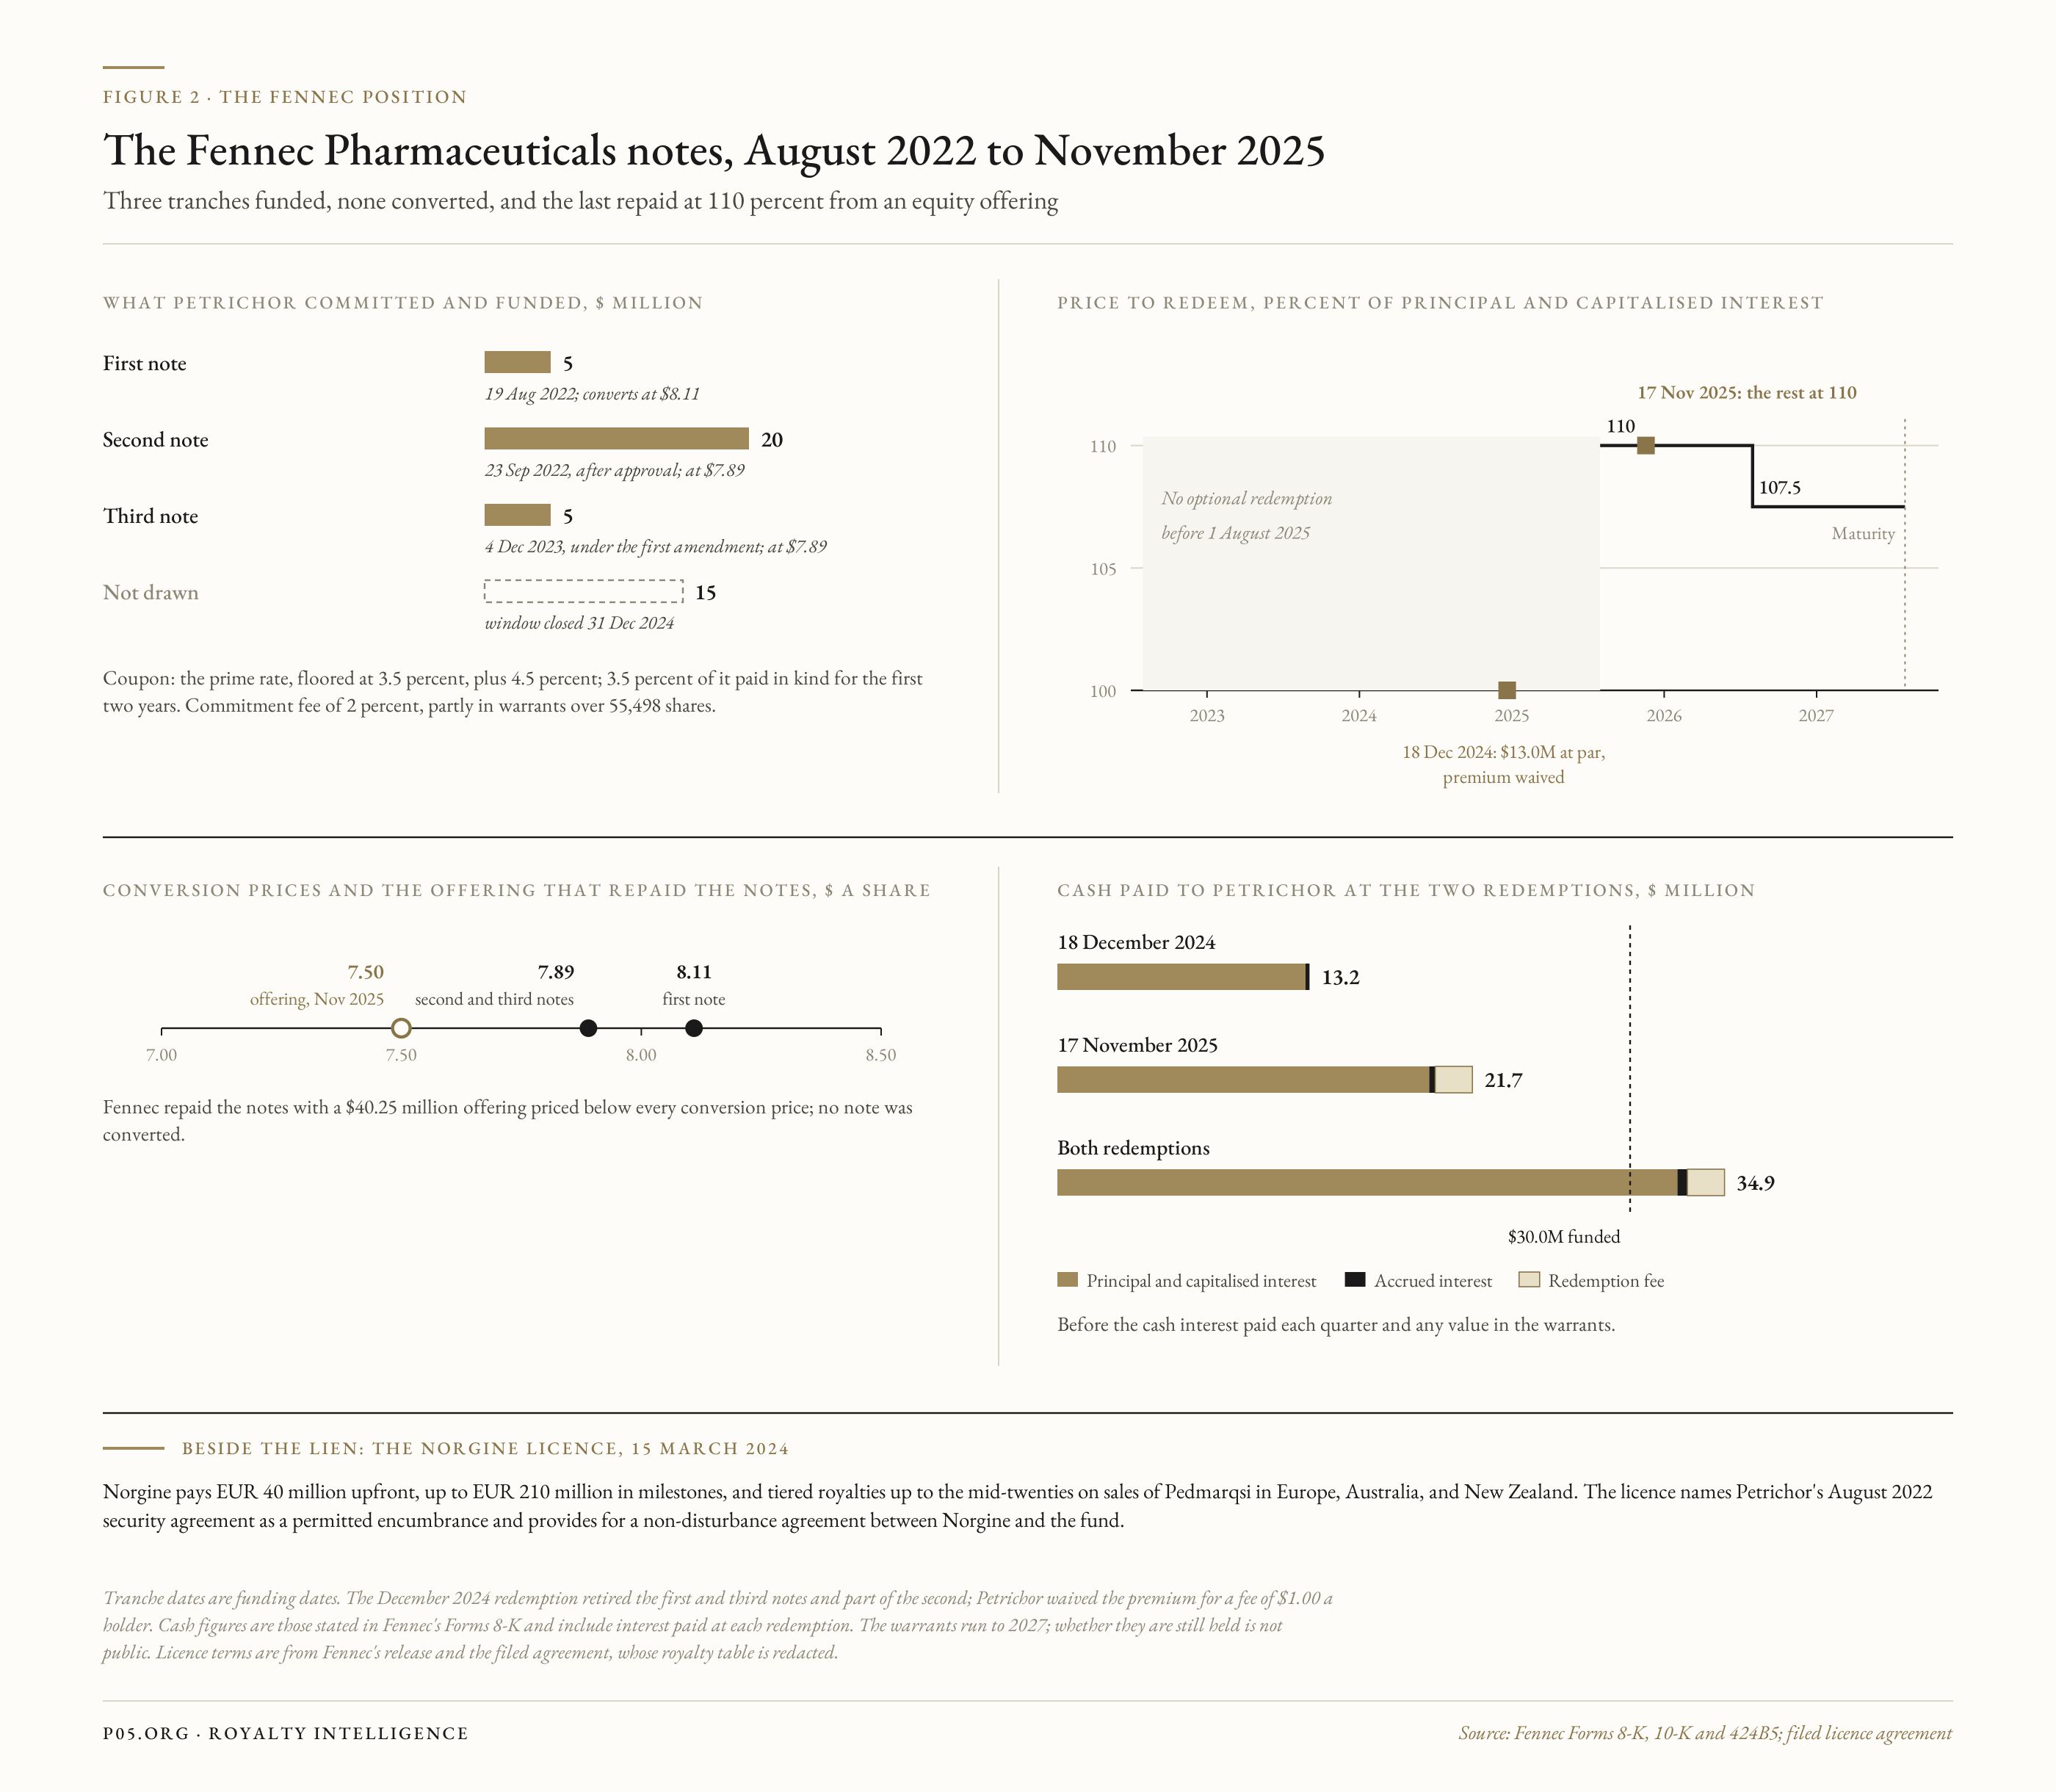
Fennec sells one product, Pedmark, a sodium thiosulfate injection that protects children's hearing during cisplatin chemotherapy. On 1 August 2022, seven weeks before the American approval, it agreed to sell Petrichor up to $45M of senior secured convertible notes.
The first $5M funded at once and converted at $8.11 a share. A second tranche of $20M depended on approval. Up to $20M more could follow by agreement. The notes ran to August 2027, and Fennec could redeem them from August 2025 at 110 percent, falling to 107.5 percent a year later. A 2 percent commitment fee was paid partly in warrants over 55,498 shares.
The $20M tranche funded on 23 September 2022 at a conversion price of $7.89. A third tranche of $5M followed in December 2023 under a first amendment, which paid its interest wholly in kind for a year and left $15M available until the end of 2024. That money was never drawn.
In March 2024 Fennec licensed the European rights. Norgine agreed to pay €40 million upfront, up to €210 million in milestones, and tiered royalties up to the mid-twenties on net sales in Europe, Australia, and New Zealand. Petrichor's security reached the intellectual property, so the licence had to deal with it.
The filed agreement names the August 2022 security agreement with Petrichor Opportunities Fund I as a permitted encumbrance, and it provides for a non-disturbance agreement between Norgine and the fund. Under such an agreement the lender undertakes that the licensee keeps its rights if the lender enforces its lien.
The Norgine royalty became a Fennec asset inside Petrichor's collateral. The notes barred Fennec from transferring certain assets or granting liens beyond those permitted, so a sale of that stream while the notes were outstanding would have needed the lender's consent.
Fennec then repaid the notes in two steps. On 18 December 2024 it redeemed the first and third notes, $13.0M of principal and capitalised interest, and Petrichor waived the premium for a fee of $1.00 per holder.
About $19.2M of the second note remained. On 13 November 2025 Fennec agreed to buy back the rest at 110 percent of principal and accrued paid-in-kind interest, and four days later it paid $21,729,455.30. Of that, $19.48M was principal with capitalised interest, $0.31M was accrued interest, and $1.95M was the redemption fee.
The cash came from shareholders. Fennec sold shares at $7.50 each in an offering of $40.25M that closed the same day, below the $7.89 at which the largest note would have converted. Over three years and three months, Petrichor funded $30.0M and received at least $34.9M in the two redemptions, before the cash interest paid quarterly and the value of its warrants. Fennec's annual report for 2025 shows no notes outstanding.
ITM and the Conversion
ITM's convertible loan is the largest financing Petrichor is known to have led. Its terms were not published. The company said in June 2023 that the loan had converted into equity as part of its round that month. The conversion made Petrichor's funds ITM shareholders. The size of their holding has not been disclosed.
Telix's announcement does not name ITM's shareholders. It says that holders of more than 90 percent of the shares signed at announcement and that the sellers' Telix shares will sit in escrow, under lock-ups of up to 15 months. ITM's sellers will own about 23.7 percent of the combined company. The milestones depend on approvals of ITM-11 between 2027 and 2031 and on its sales in 2030.
Cryoport and ClearPoint
The two notes of 2018 and 2020 show how Petrichor priced its conversions. Cryoport's $15M note paid three-month LIBOR, floored at 2 percent, plus 6 percent, converted at $13.11, and converted automatically if the shares stayed above $17.48 for 15 days. Seven months after signing, an amendment fixed the rate at 6.00 percent, removed the covenants, and set a conversion date of 14 December 2019. On that date the principal and interest became 1,172,305 shares.
ClearPoint, a maker of devices for brain surgery, issued $17.5M of secured convertible notes in January 2020, $7.5M to Petrichor and $10.0M to PTC. In December Petrichor bought a second note of $7.5M at 2 percent in cash and 5 percent in kind, converting at $10.14. Petrichor converted both in 2021. PTC's note stayed outstanding until ClearPoint repaid it in 2024.
Palvella and the Ligand Royalty
At Palvella, a developer of a topical rapamycin for rare skin diseases, Petrichor's capital sits below a royalty held by another investor. Ligand is entitled to a royalty of 8 to 9.8 percent on sales of the product, QTORIN rapamycin. The same release lists Petrichor among the equity investors that funded Palvella after Ligand's investment.
Petrichor's funds bought $5.0M of Series D preferred stock around the turn of 2023 and a $2.5M convertible note in June 2024, which converted into Palvella's placement in December at $13.9965 a share. Palvella listed through a merger with Pieris. Its shares were sold at $125 each in a February 2026 offering, for which Petrichor's main fund agreed to a lock-up.
Absent Royalties
Petrichor does not appear in the royalty surveys reviewed for this profile. Gibson Dunn's 2026 update, which tracks 133 transactions, does not mention it, and nor does the firm's report on 2020 to 2024. Full-text searches of SEC filings for Petrichor's fund names return no royalty purchase agreement, revenue interest or royalty-backed note.
The record does not say why. The 2017 proxy described an intended mandate, and the 2026 brochure describes the instruments the firm uses. PitchBook classifies the new fund as a mezzanine debt fund. Its Form D gives no strategy beyond private equity.
Blue Team
- One founder and two partners who have worked together since OrbiMed, and nine years of investing under one adviser with no disciplinary disclosures
- Notes that paid or converted. Of the convertible instruments whose outcome is public, four became shares and one was repaid in full with a 10 percent premium
- Sales of portfolio companies to large acquirers in 2025 and 2026: Novartis for Tourmaline, Lantheus for Evergreen, Alcon for control of Aurion and Telix's pending deal for ITM
- Instruments that move from debt to equity, with part of the interest paid in kind before approval and a conversion right that shares in any rise after it
- Regulatory assets that rose from $661.7M in 2021 to $966.5M in 2025
- A record of agreeing terms with a borrower's licensee, as in the Norgine non-disturbance agreement at Fennec
- Additional company-building capacity through Scion's $310M fund, and two operating partners added in 2026
Red Team
- No fund return is published, and Fund I's Form D filings stop at $153.35M, four months before the $410M close
- Petrichor Capital Partners Fund II had sold nothing when it filed in April 2025, and no close has been announced since. It does not appear among the four private funds in the March 2026 Form ADV
- The royalty mandate described in 2017 has no deal behind it in the public record
- LumiraDx, a position held since 2017, entered administration in late 2023, and Roche agreed to buy its point-of-care business. By then Petrichor held only warrants
- The outcomes of the Leukocare and Aurion notes and the Persivia debt are not public. Alcon's price for Aurion was not disclosed
- Archean's revenue share gives a third party a claim on the manager's income, capped by a return test whose level is not public
- Fennec's last note was redeemed with money raised from shareholders at $7.50 a share, below the conversion price, so the conversion right on the largest Fennec tranche was never exercised
- Petrichor's share of most private rounds is not disclosed, so the size of its largest positions cannot be measured from public sources
Implications for the Pharmaceutical Royalty and Biotech Capital Markets
Fennec financed its launch without selling any of its revenue. In 2022 it sold convertible notes to Petrichor. In 2024 it licensed Europe to Norgine and kept the royalty as income and the milestones as upside. The only investor with a claim on Fennec's revenue held it as a lender with a lien.
The Norgine non-disturbance agreement marks where those claims meet. A licence that pays royalties is an asset of the licensor, and a lender with a lien over it has a say in what happens to it. Petrichor agreed that Norgine's rights would survive enforcement.
That protected the licensee and left the royalty itself within the collateral. Any party wanting to buy Fennec's European royalty before November 2025 would have needed Petrichor's consent. Since the redemption Fennec owes Petrichor nothing.
The pricing gives a royalty buyer a comparison. Fennec paid a floating coupon of prime plus 4.5 percent, partly in kind, and 10 percent to leave after three years. On $30.0M funded, the two redemptions and the fee came to at least $34.9M before cash interest.
A royalty financing on the same product would have been priced on sales, would have had no conversion feature, and would have carried a cap and a buy-out schedule of the kind described in the Oaktree and Perceptive profiles.
The record does not show which would have cost Fennec less. The convertible gave Fennec the chance to repay in shares and gave Petrichor a call on a rising price that did not come.
At Palvella the two kinds of capital sit together. Ligand's royalty and Petrichor's shares draw on one product, and the royalty is paid from sales before any value reaches the shares. A royalty fund bidding for a stake beside Ligand's would meet Petrichor as a shareholder and director.
The fund's next move is not public. Fund II is registered and classified by a data provider as mezzanine debt. If Telix's purchase of ITM closes, any ITM shares that Petrichor's funds still hold will be exchanged for Telix shares held in escrow.
Recent Developments
- Telix agrees to buy ITM for $1.65B upfront and up to $700M in milestones, with ITM shareholders to receive Telix shares in escrow, on 21 September 2026
- Petrichor names Don Hardison as operating partner on 20 May 2026
- Petrichor names Paul Sekhri as operating partner on 1 April 2026
- The adviser files its annual Form ADV with regulatory assets of $966.5M and a new chief compliance officer on 31 March 2026
- Palvella prices an offering at $125 a share, with Petrichor's main fund locked up, in February 2026
- Fennec redeems its remaining Petrichor notes for $21.7M on 17 November 2025
- Novartis completes its acquisition of Tourmaline at $48.00 a share on 28 October 2025
- Petrichor Capital Partners Fund II files its Form D, with no sales, on 17 April 2025
- Lantheus completes its acquisition of Evergreen Theragnostics on 1 April 2025
- Alcon acquires a majority interest in Aurion Biotech on 26 March 2025
- No Petrichor royalty, revenue interest or royalty-backed note has been identified at any date
Financial History and Recent Developments
| Date | Event |
|---|---|
| Jan 2017 | Petrichor formed; Archean Capital Partners I commits $100M of seed capital |
| Feb 2017 | First investment found: about $5.0M of LumiraDx shares |
| 14 Jul 2017 | Fund I files its first Form D, $100M sold to one investor |
| 2 Jan 2018 | Adviser registers with the SEC |
| 14 Dec 2018 | Cryoport: $10M of shares and a $15M convertible note |
| 20 Sep 2019 | LumiraDx term loan of $40.0M, led by Kennedy Lewis; prepaid October 2020 |
| Oct 2019 | Persivia growth financing of $15M; CorneaGen Series B |
| 14 Dec 2019 | Cryoport note converts into 1,172,305 shares |
| 29 Jan 2020 | ClearPoint convertible notes, $7.5M from Petrichor and $10.0M from PTC |
| 2 Nov 2020 | Fund I closes at $410M |
| 29 Dec 2020 | Second ClearPoint note, $7.5M |
| Apr 2021 | POF I Co-Invest sells $37.0M; ITM convertible loan of $109M (EUR 90M) |
| 23 Jun 2021 | Leukocare: $15M convertible loan and $2.5M of equity |
| 2021 | Both ClearPoint notes converted |
| Apr 2022 | First Tourmaline investment, $5M |
| 1 Aug 2022 | Fennec: up to $45M of secured convertible notes |
| 23 Sep 2022 | Fennec draws $20M after Pedmark is approved |
| Jan 2023 | VERO Biotech round of $30M, led by Petrichor; Palvella Series D |
| 9 May 2023 | Ascend Series A, co-led with Abingworth |
| Jun 2023 | ITM loan converts into equity |
| 4 Dec 2023 | Fennec draws $5M under a first amendment |
| Feb 2024 | Scion Life Sciences closes at $310M |
| 15 Mar 2024 | Fennec licenses Pedmarqsi to Norgine; Petrichor security named as a permitted encumbrance |
| 28 Mar 2024 | Avalo placement, with preferred stock and warrants |
| 16 Apr 2024 | Evergreen Theragnostics round of $26M |
| 26 Jun 2024 | Palvella convertible notes, alongside Ligand |
| 18 Dec 2024 | Fennec redeems $13.0M of notes |
| 8 Jan 2025 | Geneoscopy Series C of $105M, led by Bio-Rad |
| 26 Mar 2025 | Alcon takes control of Aurion |
| 1 Apr 2025 | Lantheus completes its purchase of Evergreen |
| 17 Apr 2025 | Fund II files its Form D |
| 28 Oct 2025 | Novartis completes its purchase of Tourmaline |
| 17 Nov 2025 | Fennec redeems the remaining notes for $21.7M |
| 31 Mar 2026 | Form ADV reports $966.5M |
| 21 Sep 2026 | Telix agrees to buy ITM |
Conclusion
Petrichor raised $410M for its main fund and $310M for a company-creation affiliate, and it reported regulatory assets of about $966.5M at the end of 2025. Its credit has taken the form of convertible notes and the odd shared term loan, priced on a floored rate with part of the interest in kind and a premium for early repayment. Most of those notes became shares. Its equity has mostly left through sales of companies to large acquirers such as Novartis and Lantheus.
Royalties were in the description of the firm that its seed investor gave in 2017, and they have not entered the record since. At Fennec a royalty sat inside Petrichor's collateral, protected by an agreement that let Norgine keep its licence. At Palvella one ranks ahead of Petrichor's shares.
The ITM sale is next. Telix's shareholders are expected to vote on the deal at a meeting in November, and Telix expects to close it by the end of its 2026 financial year. If Petrichor's funds still hold the shares that came from the loan they led in 2021, those shares will become Telix stock held in escrow.
All information in this report was accurate as of the research date and is derived from publicly available sources including court opinions, regulatory guidance, academic literature, SEC filings, and financial news reporting. Information may have changed since publication. This content is for informational purposes only and does not constitute investment, legal, or financial advice. The author is not a lawyer or financial adviser.